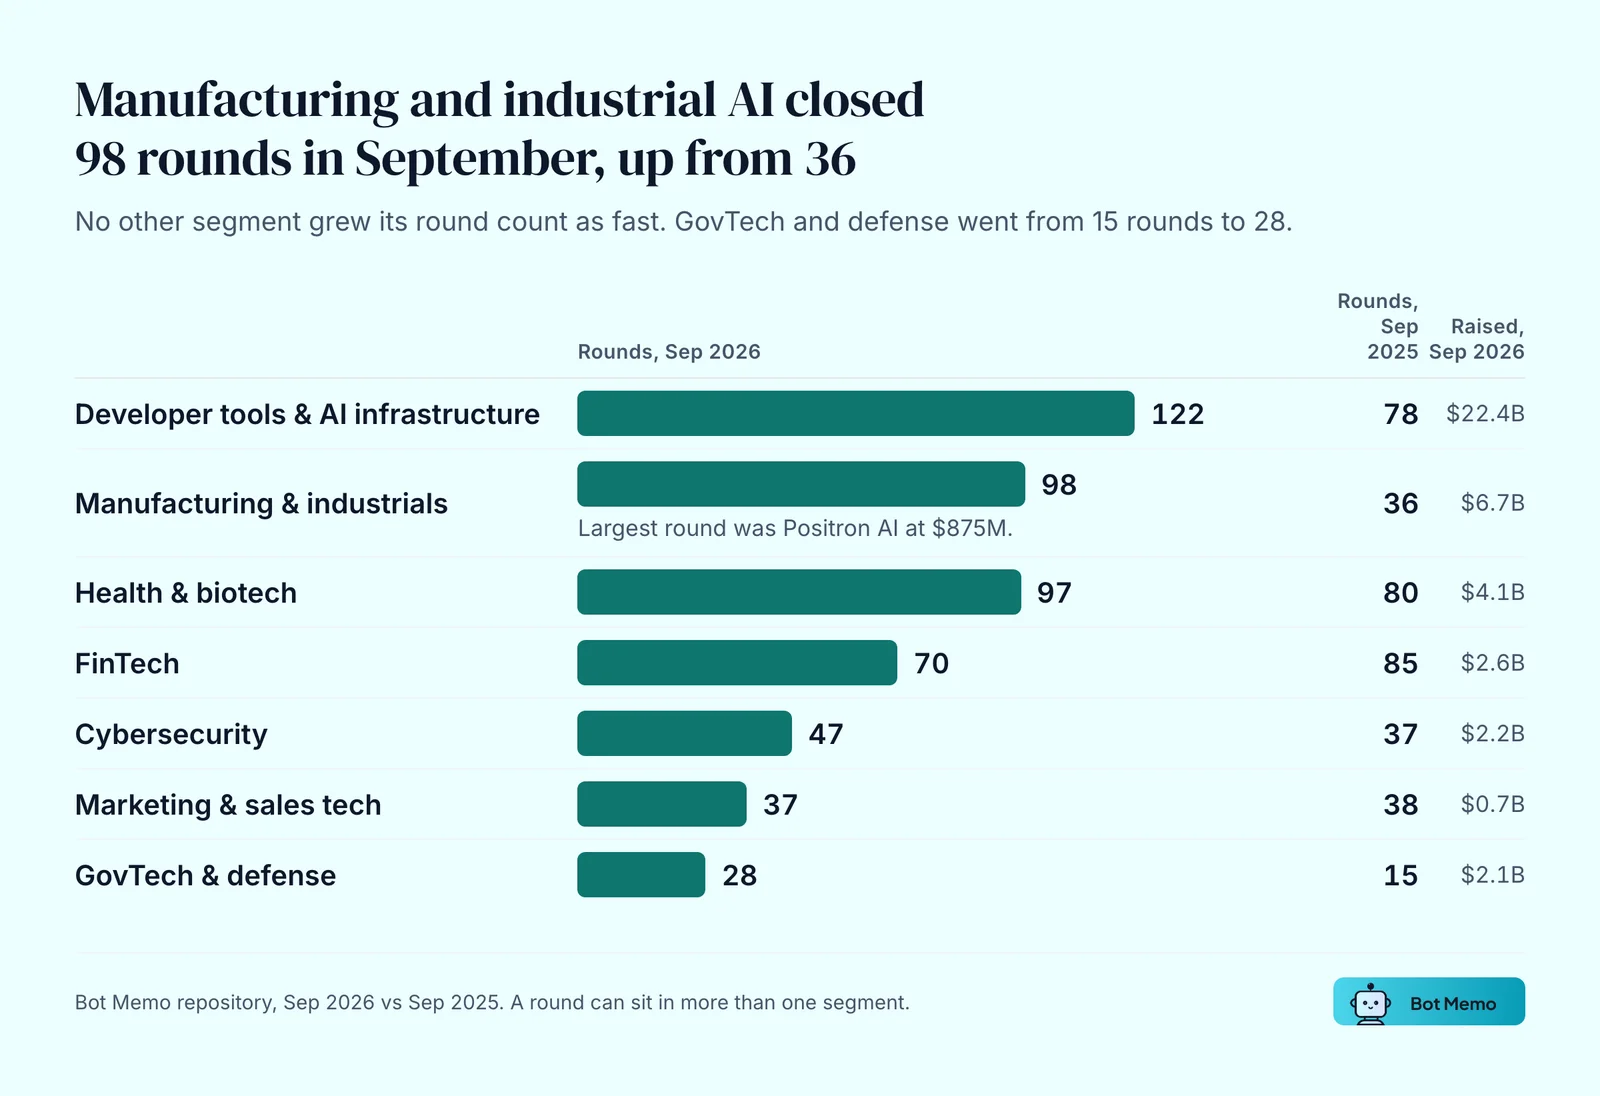

555 venture AI rounds closed in September, worth $40.1B. In September 2025 it was 512 rounds worth $37.6B. Manufacturing and industrial AI companies closed 98 of this September’s rounds, up from 36 a year earlier, and no other industry segment grew its round count as fast.
On this page
Industrial and defense rounds
Manufacturing and industrial AI raised $6.7B across those 98 rounds, up from $5.6B, at a $16.5M median round. The largest was Positron AI at $875M. Across the whole month, 51 rounds went to industrial automation companies and 26 to AI chip companies.
The backers who showed up most often in the segment were Atreides Management, Eclipse Ventures, Maverick Silicon, Hudson River Trading and Sequoia Capital. Maverick Silicon sat on five rounds in September, four of them at Series B or later.
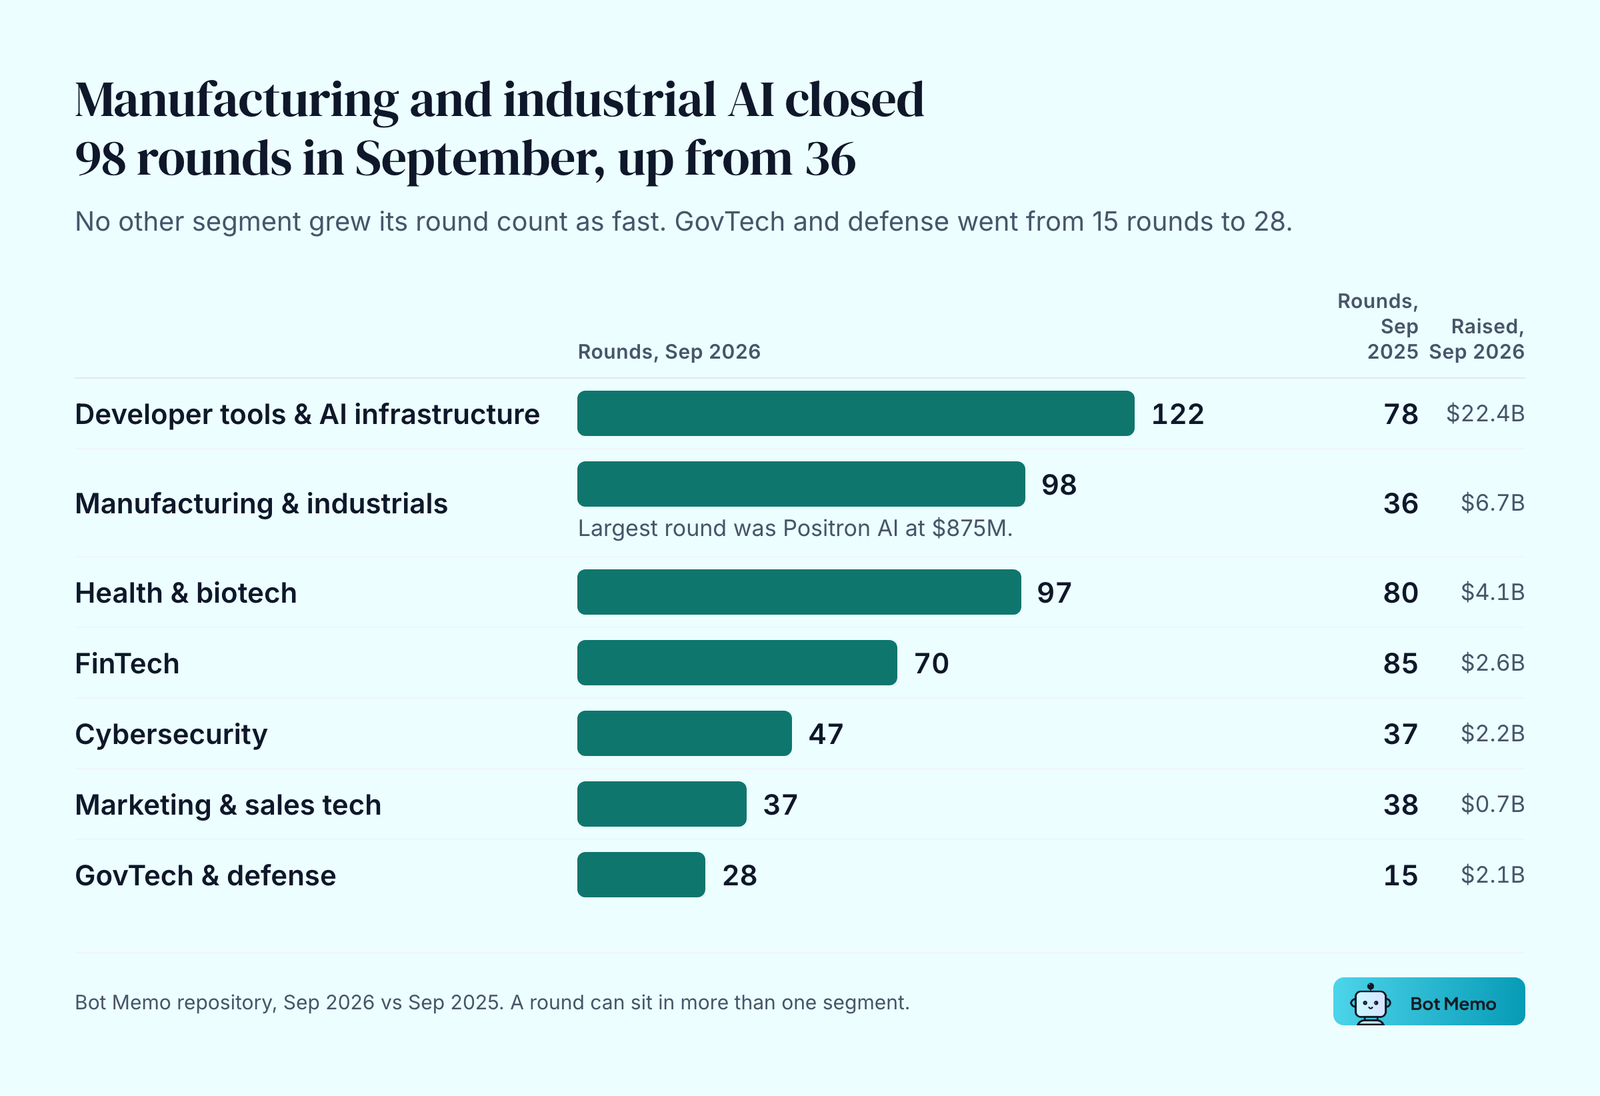
Defense moved the same way. GovTech and defense closed 28 rounds against 15, and raised $2.1B against $0.6B. The largest round was Mach Industries at $600M. The segment's most frequent backers were High-Tech Gründerfonds, Vsquared Ventures, Founders Fund, Lux Capital and 8VC. Cybersecurity went from 37 rounds to 47 and from $0.8B to $2.2B.
FinTech went the other way, 70 rounds against 85.
Infrastructure money moved to AI Adjacent
We sort the companies in our repository into four AI classifications. AI Platforms build the models and core infrastructure others build on. AI Native companies exist because of AI. AI Augmented companies added AI to a business that already worked. AI Adjacent companies sell what the buildout consumes, from power to data center capacity.
AI Adjacent companies closed 68 rounds, 12.3% of the month, and took 30.5% of the dollars. A year ago 74 AI Adjacent rounds took 19.5%. Crusoe's $3.9B and Nscale's $3.36B account for most of that. AI Platforms closed 17 rounds and took 19.1%, with Mistral's $3.33B the largest. A year ago seven AI Platforms rounds took 43.0%, and Anthropic's $13B was one of them.
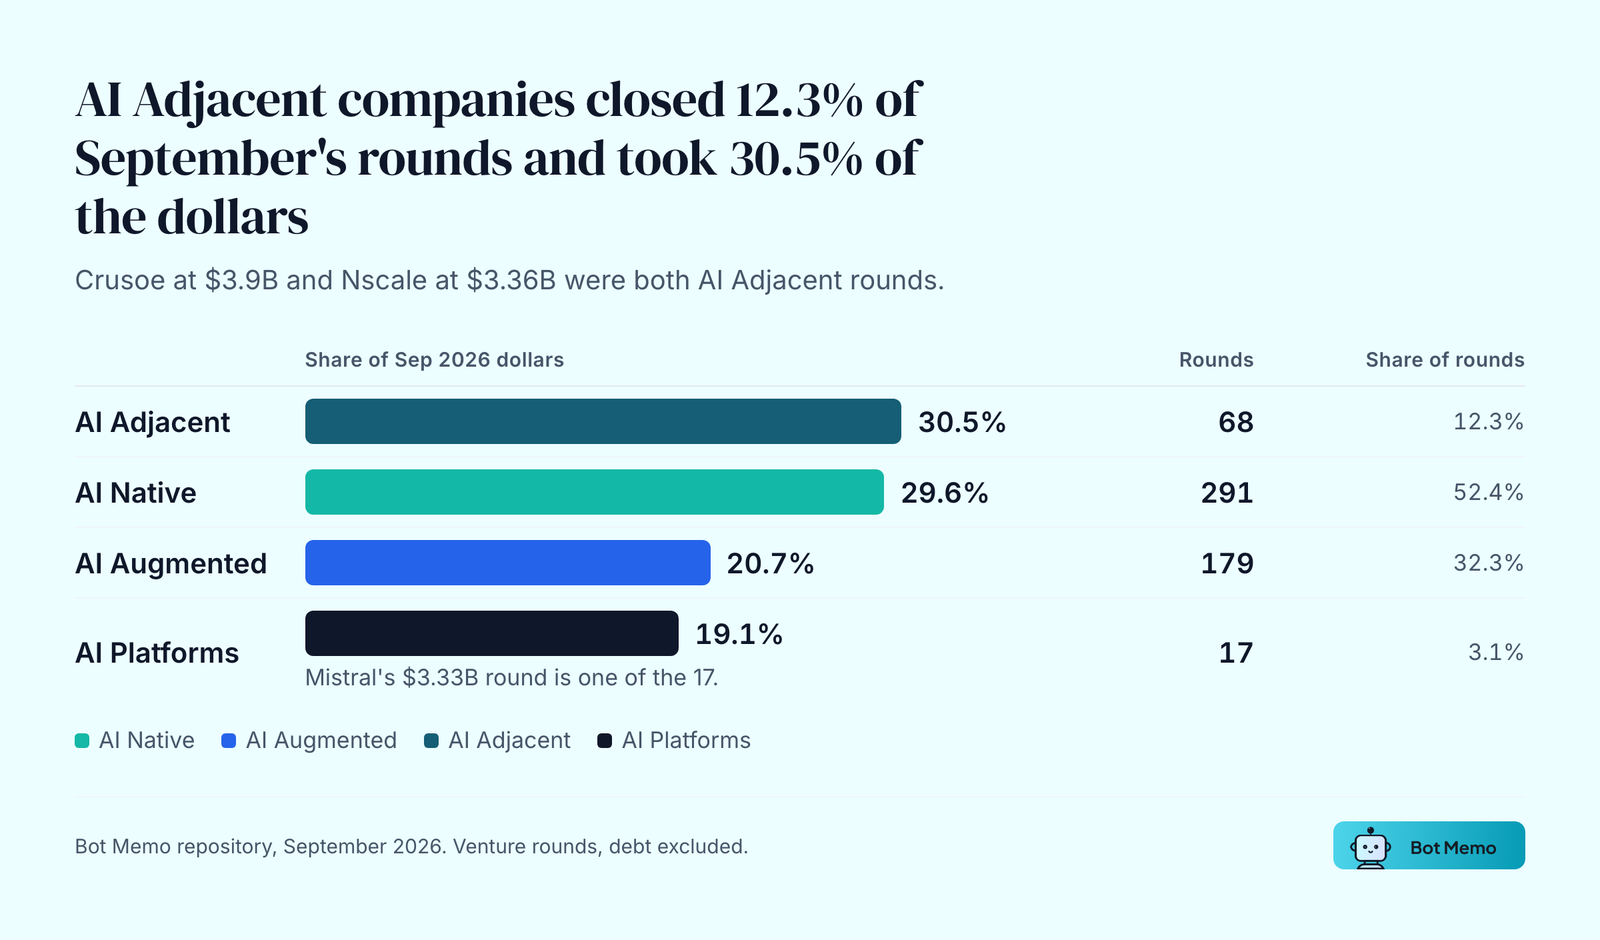
AI Native companies closed 291 rounds, 52.4% of the month, up from 46.9%. They raised $11.9B against $7.5B. Six rounds of $1B or more took 37.6% of September’s dollars; a year earlier seven took 53.4%.
Smallest at entry, ahead of AI Augmented by growth
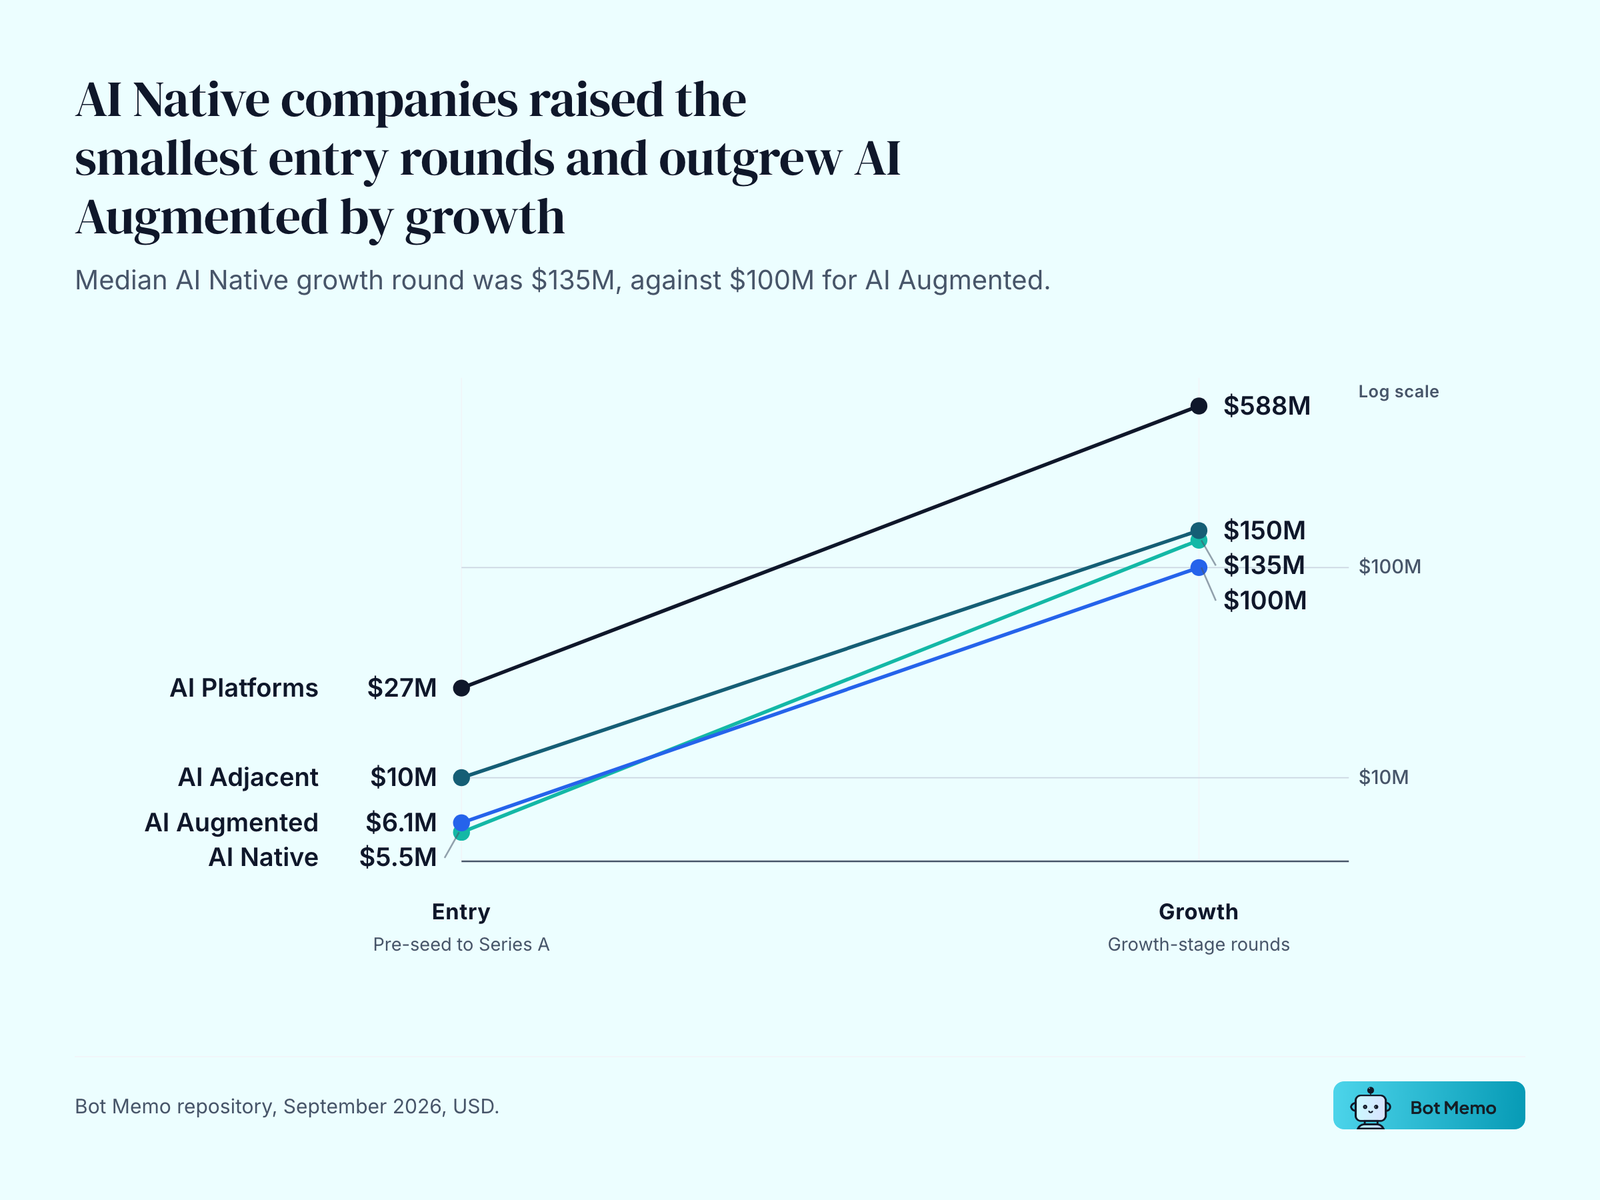
At pre-seed through Series A, AI Native companies raised the smallest rounds of the four: a $5.5M median, against $6.1M for AI Augmented, $10.0M for AI Adjacent and $26.7M for AI Platforms.
By growth, the median AI Native round was $135M and AI Augmented’s was $100M. AI Platforms growth rounds ran at a $587.5M median.
Seed got cheaper. 228 seed and pre-seed rounds closed at a $4.0M median, against 203 at $4.7M a year ago. Across all early rounds the median fell from $7.0M to $6.0M.
Who showed up
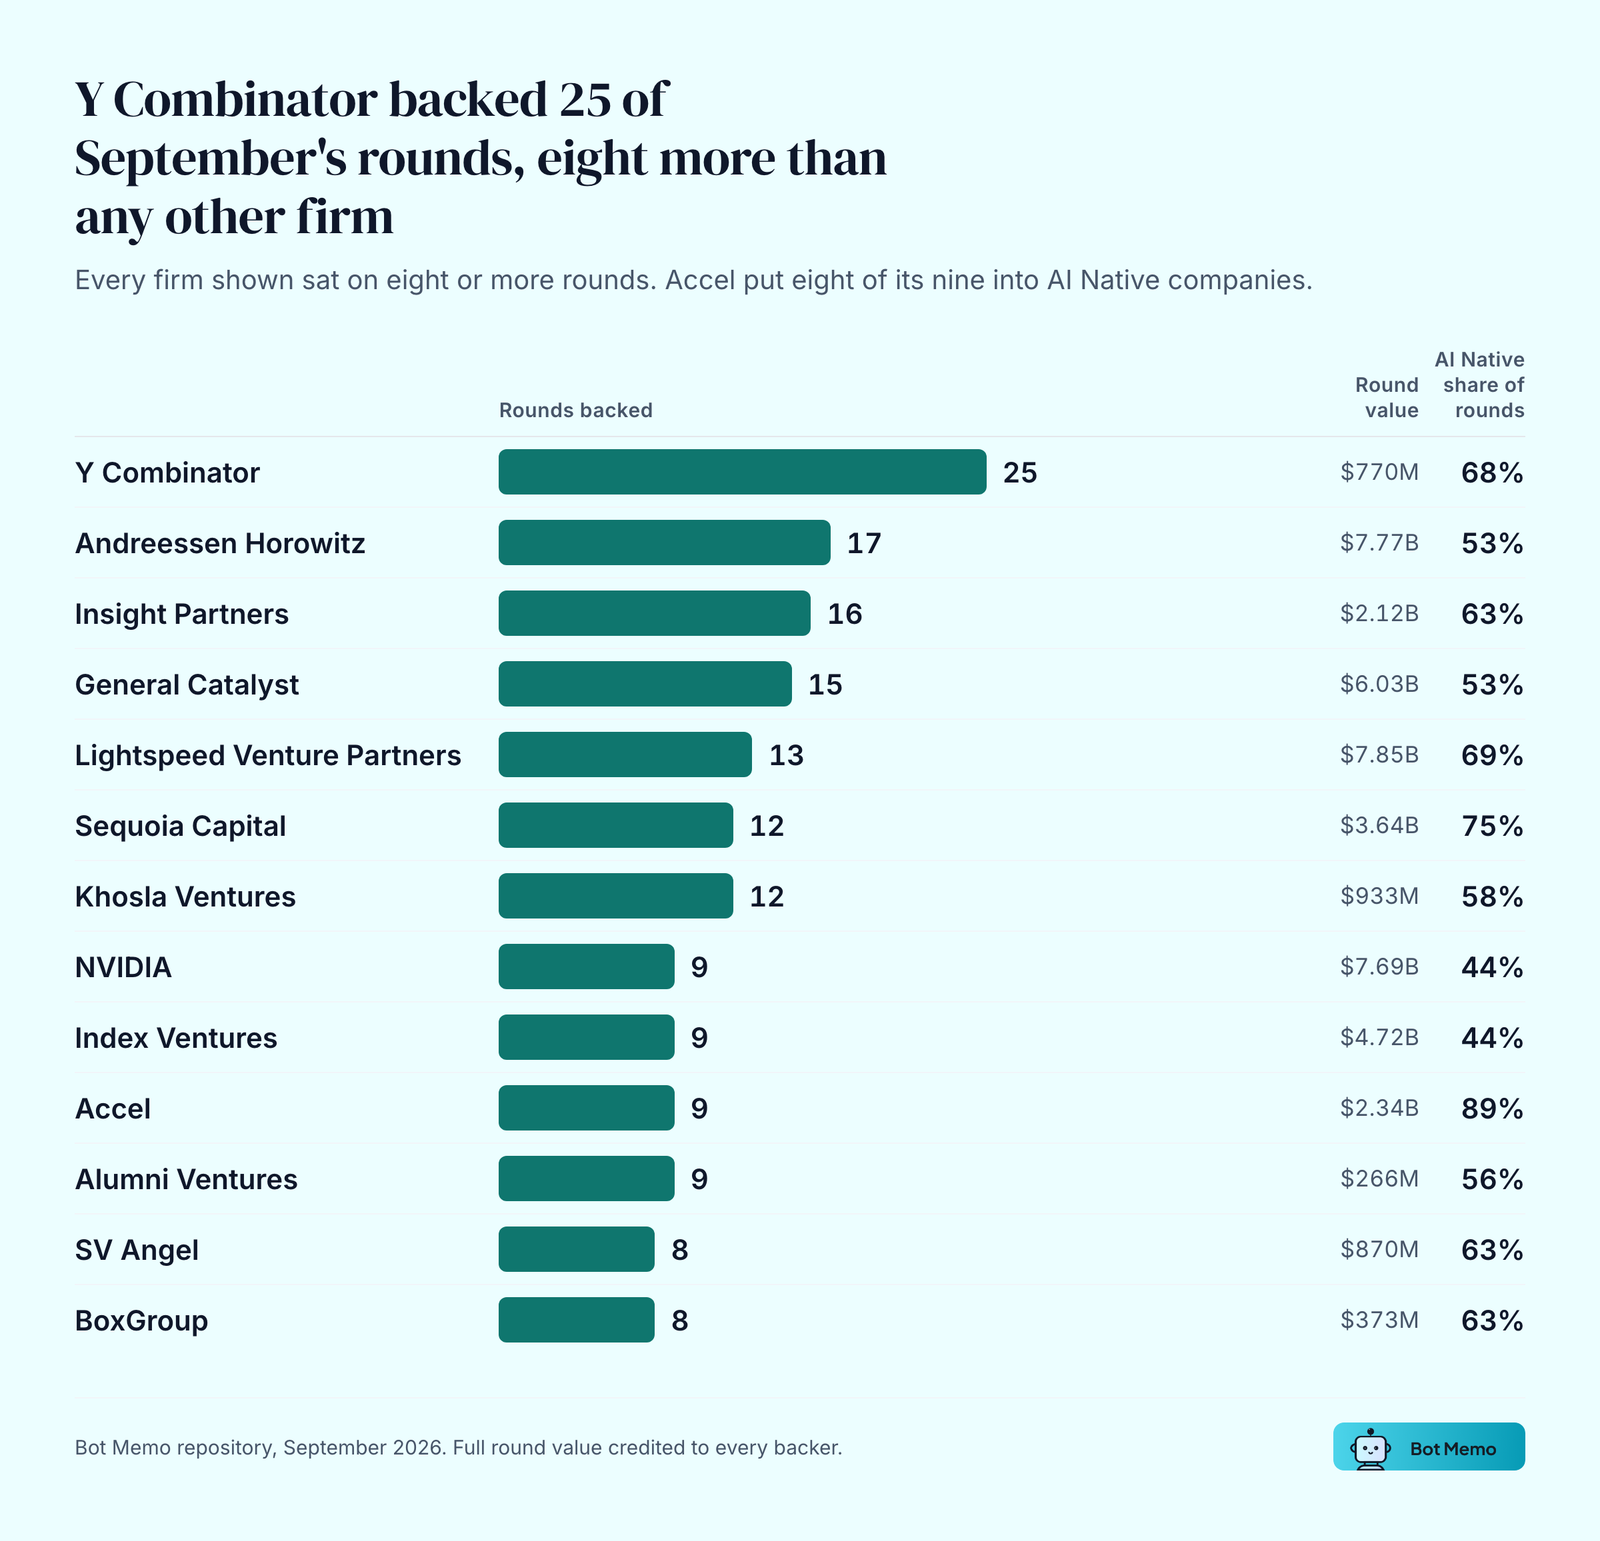
Y Combinator backed 25 rounds, eight more than anyone else. Seventeen of the 25 were AI Native companies, 19 were pre-seed through Series A, and 18 were in the US. The median round it sat in was $10M.
Andreessen Horowitz backed 17 and participated in deals worth $7.77B, at a $109M median. Its book included Mistral, Cognition at $2B, Harvey and Temporal. Insight Partners backed 16, and five of them went to AI Augmented companies, the highest count among the most active firms. General Catalyst backed 15, and five of those were health companies.
Accel put eight of its nine rounds into AI Native companies, the most AI Native book of any firm on eight or more rounds. Sequoia Capital put nine of its 12 there, at a $190M median round, and four of the 12 were cybersecurity companies. Lightspeed Venture Partners backed 13 rounds with no AI Augmented company among them. Khosla Ventures also backed 12. NVIDIA’s nine split four AI Native, three AI Adjacent and two AI Platforms.
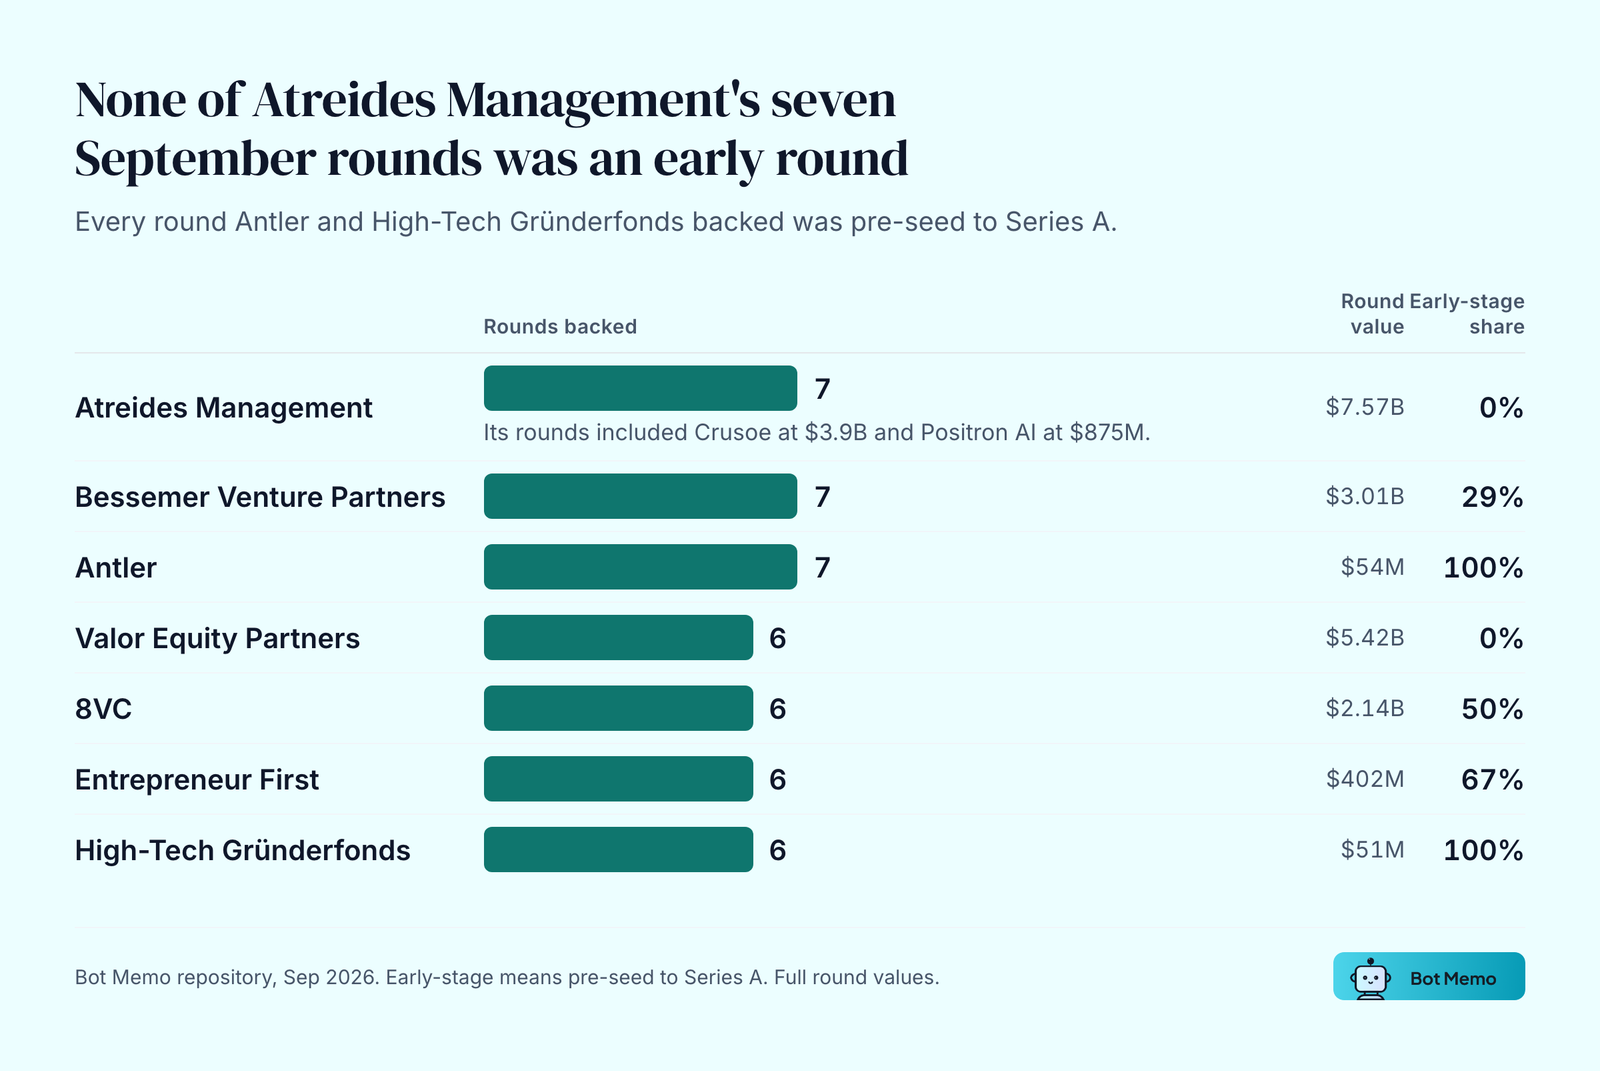
Below that tier, Atreides Management sat on seven rounds worth $7.57B in participated value, none of them early, including Crusoe and Positron AI. Bessemer Venture Partners backed seven worth $3.01B. Antler and High-Tech Gründerfonds backed seven and six, and every one was pre-seed through Series A.
Companies building AI agents closed 152 rounds for $8.2B at a $9.9M median. A year ago it was 178 rounds and $21.1B, with Anthropic's $13B among them. Sequoia, Andreessen Horowitz, Y Combinator and Khosla Ventures backed eight agent rounds each; Accel, Index Ventures and General Catalyst backed seven.
Europe's early share
Europe closed 156 rounds for $11.4B, against 121 rounds and $5.7B a year earlier. Its 112 early rounds made up 32.3% of the world’s early rounds, up from 27.6%. France had 18 rounds against eight. The UK had 42, against 41.
High-Tech Gründerfonds backed six European rounds, more than any other investor there. The European Innovation Council, Entrepreneur First, Vento and Y Combinator backed five each.
If you build industrial or defense AI and are raising now: would you rather pitch the specialists that showed up most in September, or the generalists with the largest books?
Data: Bot Memo repository, 555 venture AI rounds, September 2026, all amounts USD, debt excluded. Full round value is attributed to every participating investor, so participated totals are never summed to a market figure.
About the author
Editorial Staff
The Editorial Staff at Bot Memo is a team of writers, analysts, and AI agents dedicated to mapping the global AI startup ecosystem. Led by Chintan Zalani, the team tracks thousands of funding rounds, classifies companies across verticals, and distills it all into actionable intelligence for investors and founders.