
382 venture AI rounds closed in August, worth $29.7B. In August 2025 it was 351 rounds worth $9.9B. Eight rounds came in at $1B or more this August and took 50.3% of the month's dollars. A year earlier none did.
NVIDIA's name is on four of those eight.
On this page
NVIDIA's August book
NVIDIA backed 11 rounds in August and participated in deals worth $6.89B, the largest total of the three firms with ten or more rounds. Andreessen Horowitz sat on 12 rounds worth $3.63B. Y Combinator sat on 19 worth $2.05B.
The four big ones were Firmus at $2B, SB Energy at $1.5B, River AI at $1.1B and Poolside at $1B. On SB Energy and Poolside, NVIDIA was the only disclosed backer. The median disclosed round NVIDIA sat in was $325M.
Six of the 11 went to AI Adjacent companies, the ones selling what the buildout consumes: compute, power, chips, cloud capacity. Across the whole month AI Adjacent was 12.0% of rounds. SB Energy, Volta and Emerald AI sit in energy as well as infrastructure, and all 11 rounds landed in developer tools and AI infrastructure.
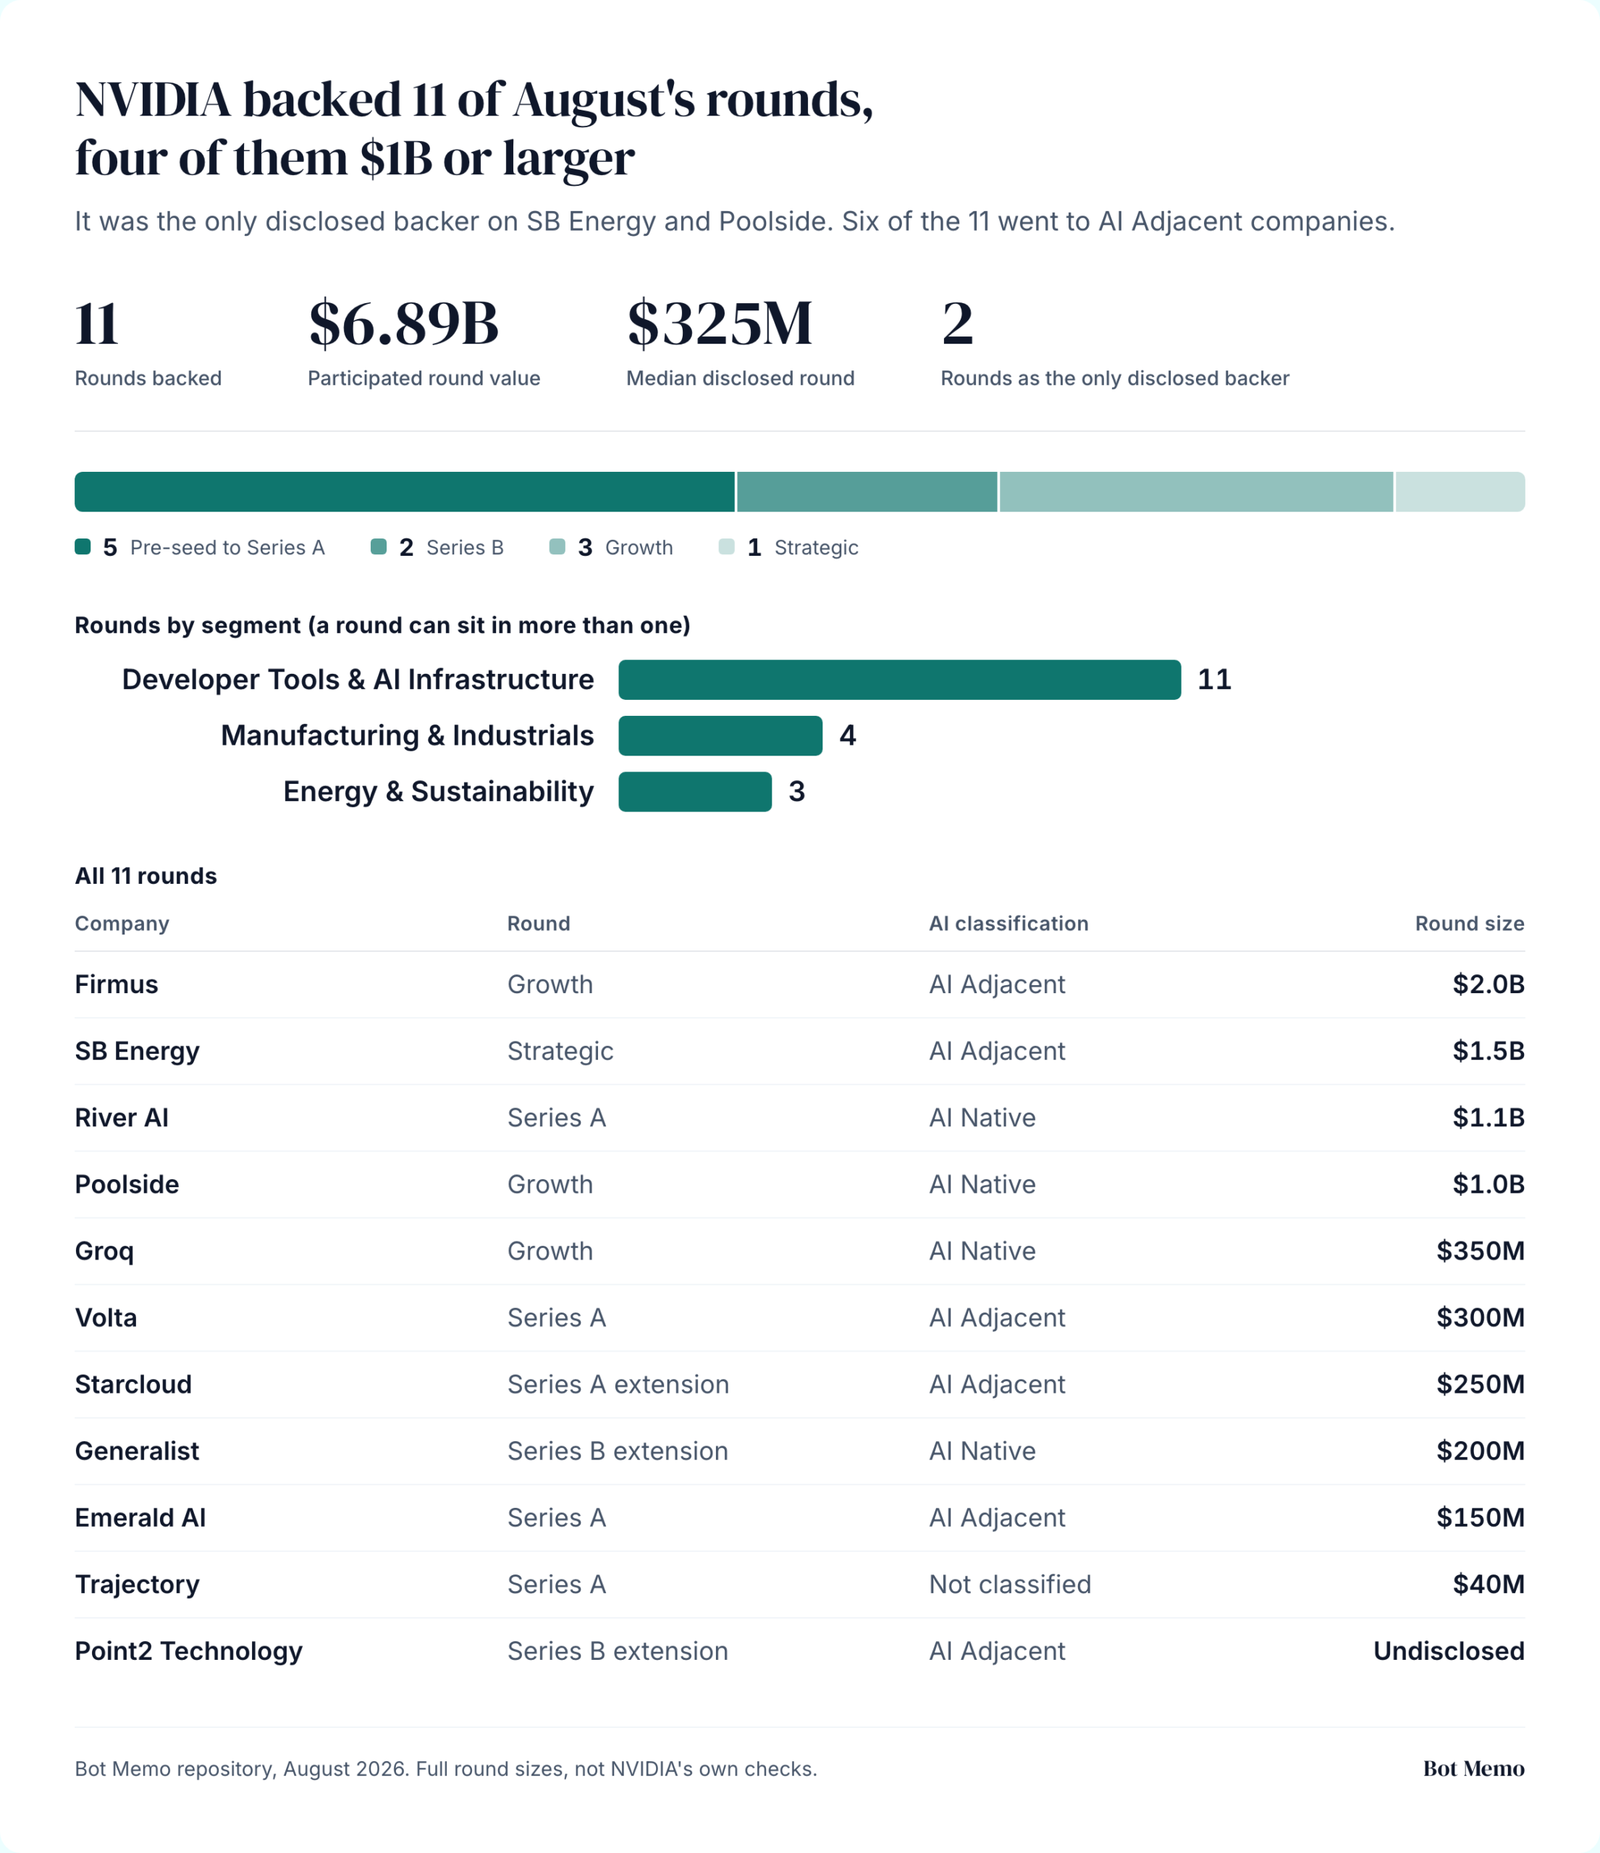
If you build the physical layer AI runs on, NVIDIA's AI Adjacent rounds in August ran from Emerald AI's $150M Series A to Firmus at $2B. If you build applications, its August book has little for you. The AI Native companies it backed were Poolside, Groq, River AI and Generalist, and all four sit in developer tools and AI infrastructure.
Thirteen rounds, a fifth of the dollars
We sort the companies in our repository into four AI classifications. AI Platforms build the models others rent. AI Native companies exist because of AI. AI Augmented companies added AI to a business that already worked. AI Adjacent companies sell what the buildout consumes.
AI Platforms closed 13 rounds, 3.4% of the month, and took 21.0% of the dollars. Databricks' $5B round is most of that. AI Native companies closed 224 rounds, 58.6% of the month, and took 34.1% of the dollars. AI Adjacent turned 46 rounds into 24.8% of the dollars.
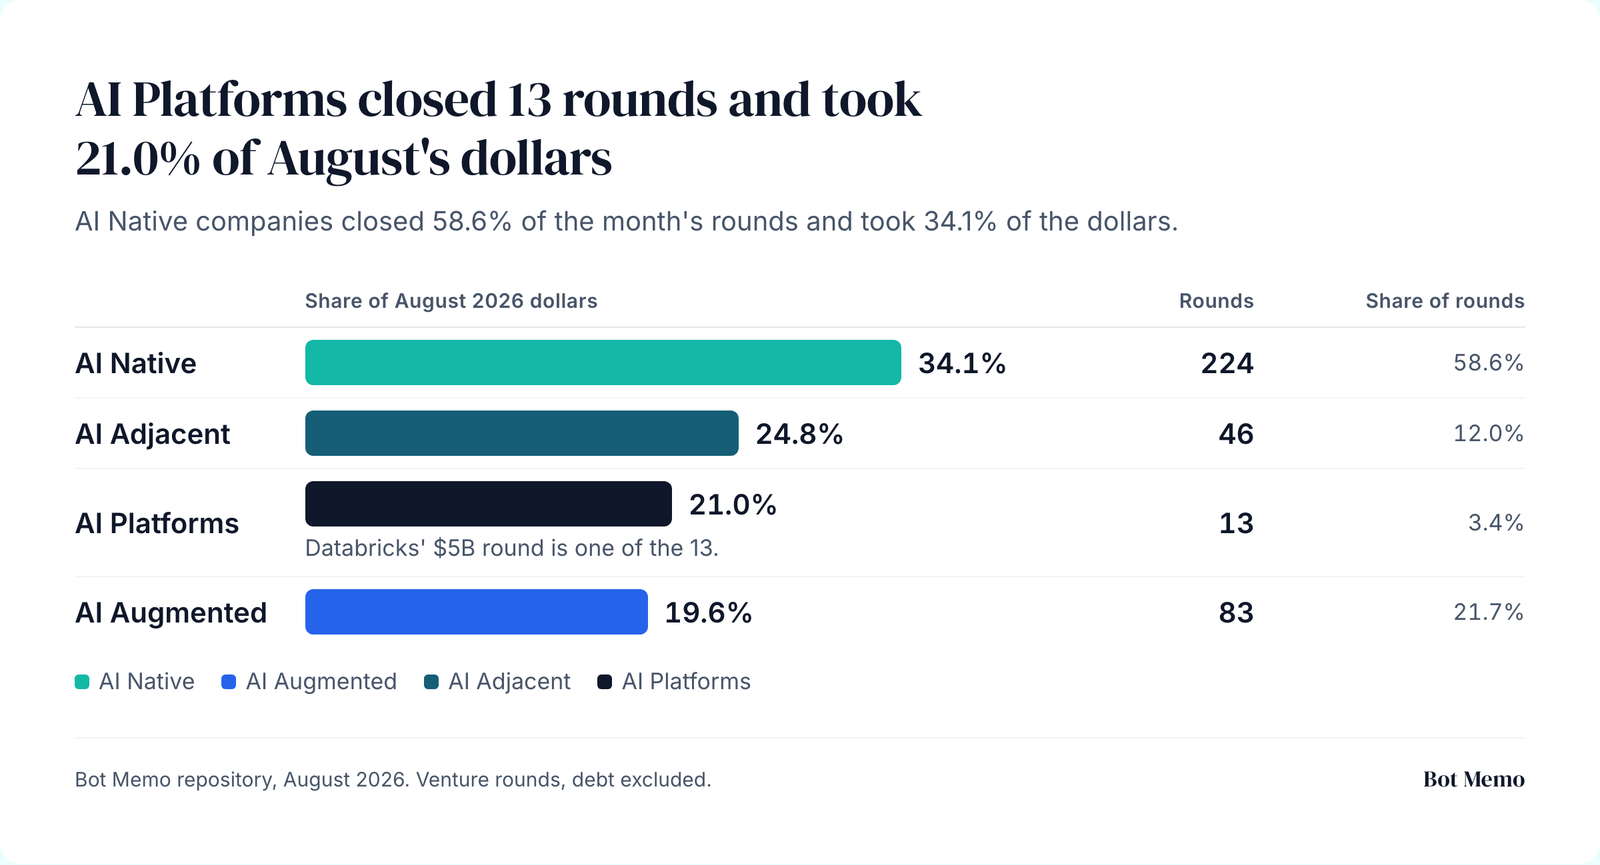
AI Augmented is the only class that closed fewer rounds than a year ago, 83 against 154, and its share of rounds fell from 43.9% to 21.7%.
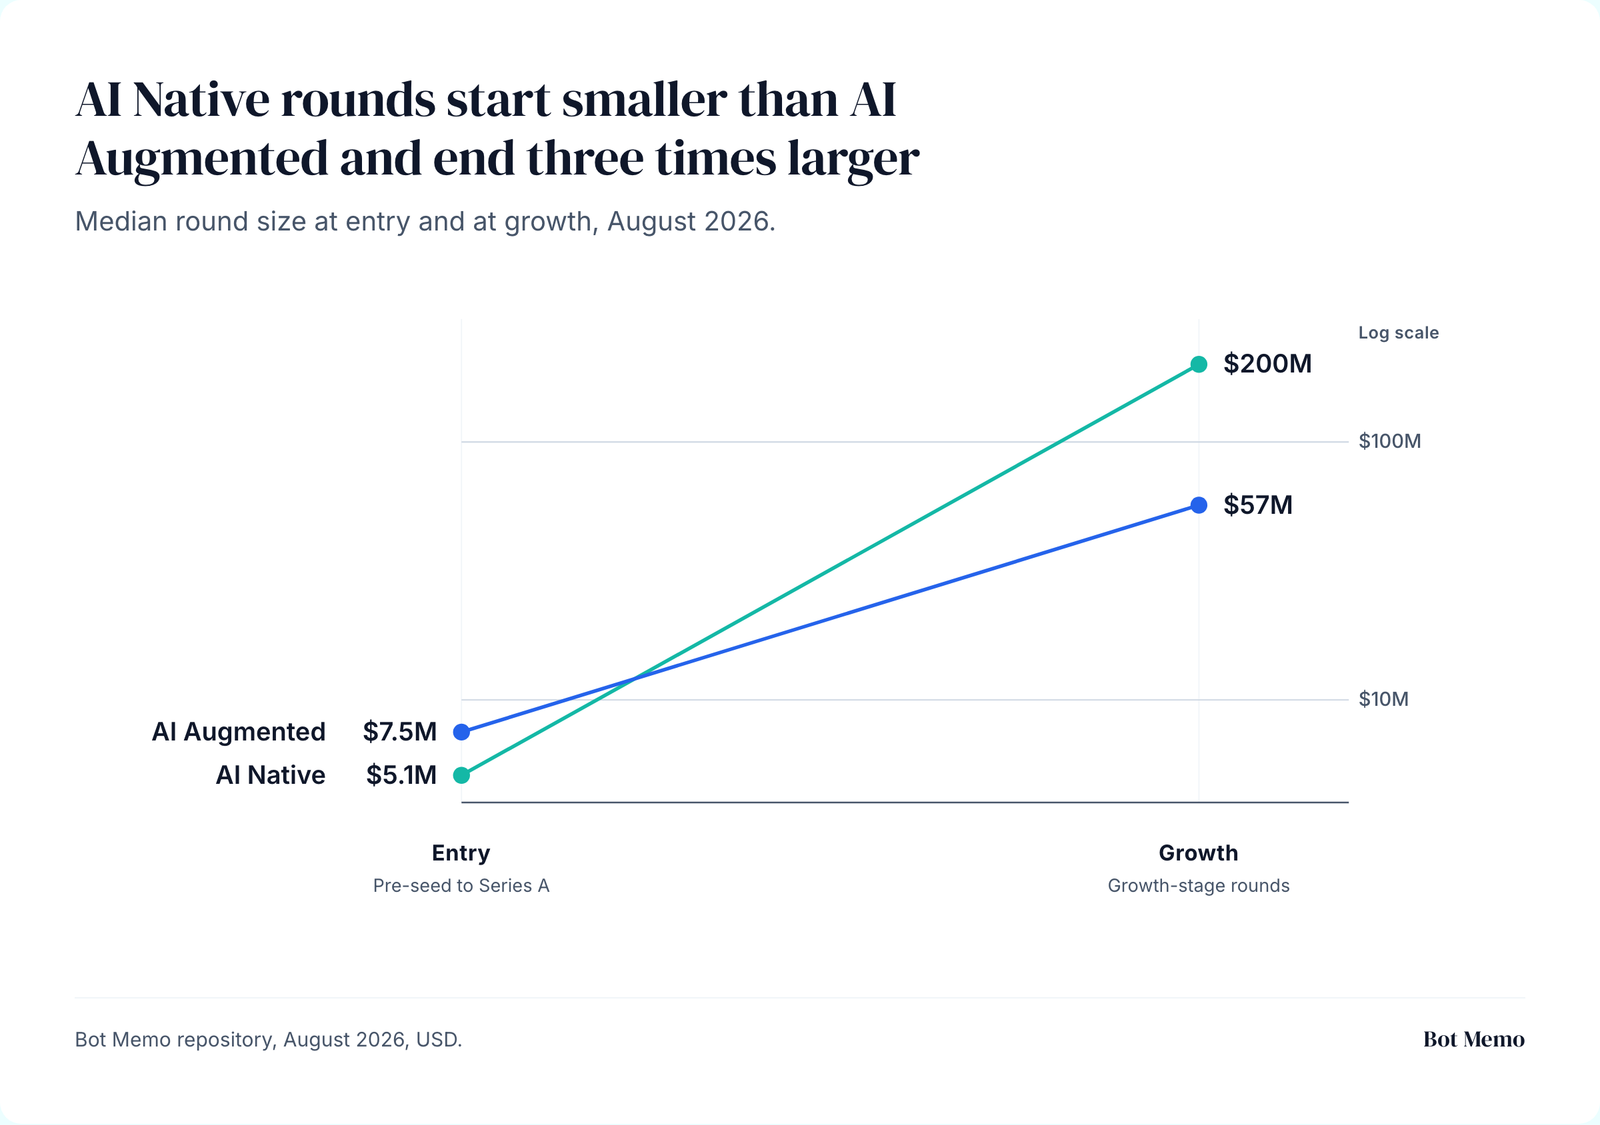
AI Native starts smallest and ends three times bigger than AI Augmented
At entry, pre-seed through Series A, AI Native companies raised the smallest rounds on the board. The median was $5.1M, against $7.5M for AI Augmented, $9.0M for AI Adjacent and $35.5M for AI Platforms.
By growth the two swap places. The median AI Native growth round was $200M, more than three times AI Augmented's $57M.
Who showed up
Y Combinator backed 19 rounds, seven more than anyone else. Fourteen of the 19 were AI Native companies, 15 were pre-seed through Series A, and 11 were in developer tools and AI infrastructure. The median round it sat in was $15M.
Andreessen Horowitz backed 12, with a $125M median round. Its book ran from Mara's $7M pre-seed to Hadrian's $1.37B Series D, and three of the 12 were defense companies.
Khosla Ventures backed eight, and four of them went to AI Platforms companies: Sarvam AI, Corma, Veeda Innovation and General Intuition. AI Platforms were 3.4% of the month's rounds. Two of those four were seed rounds, at $60M and $90M.
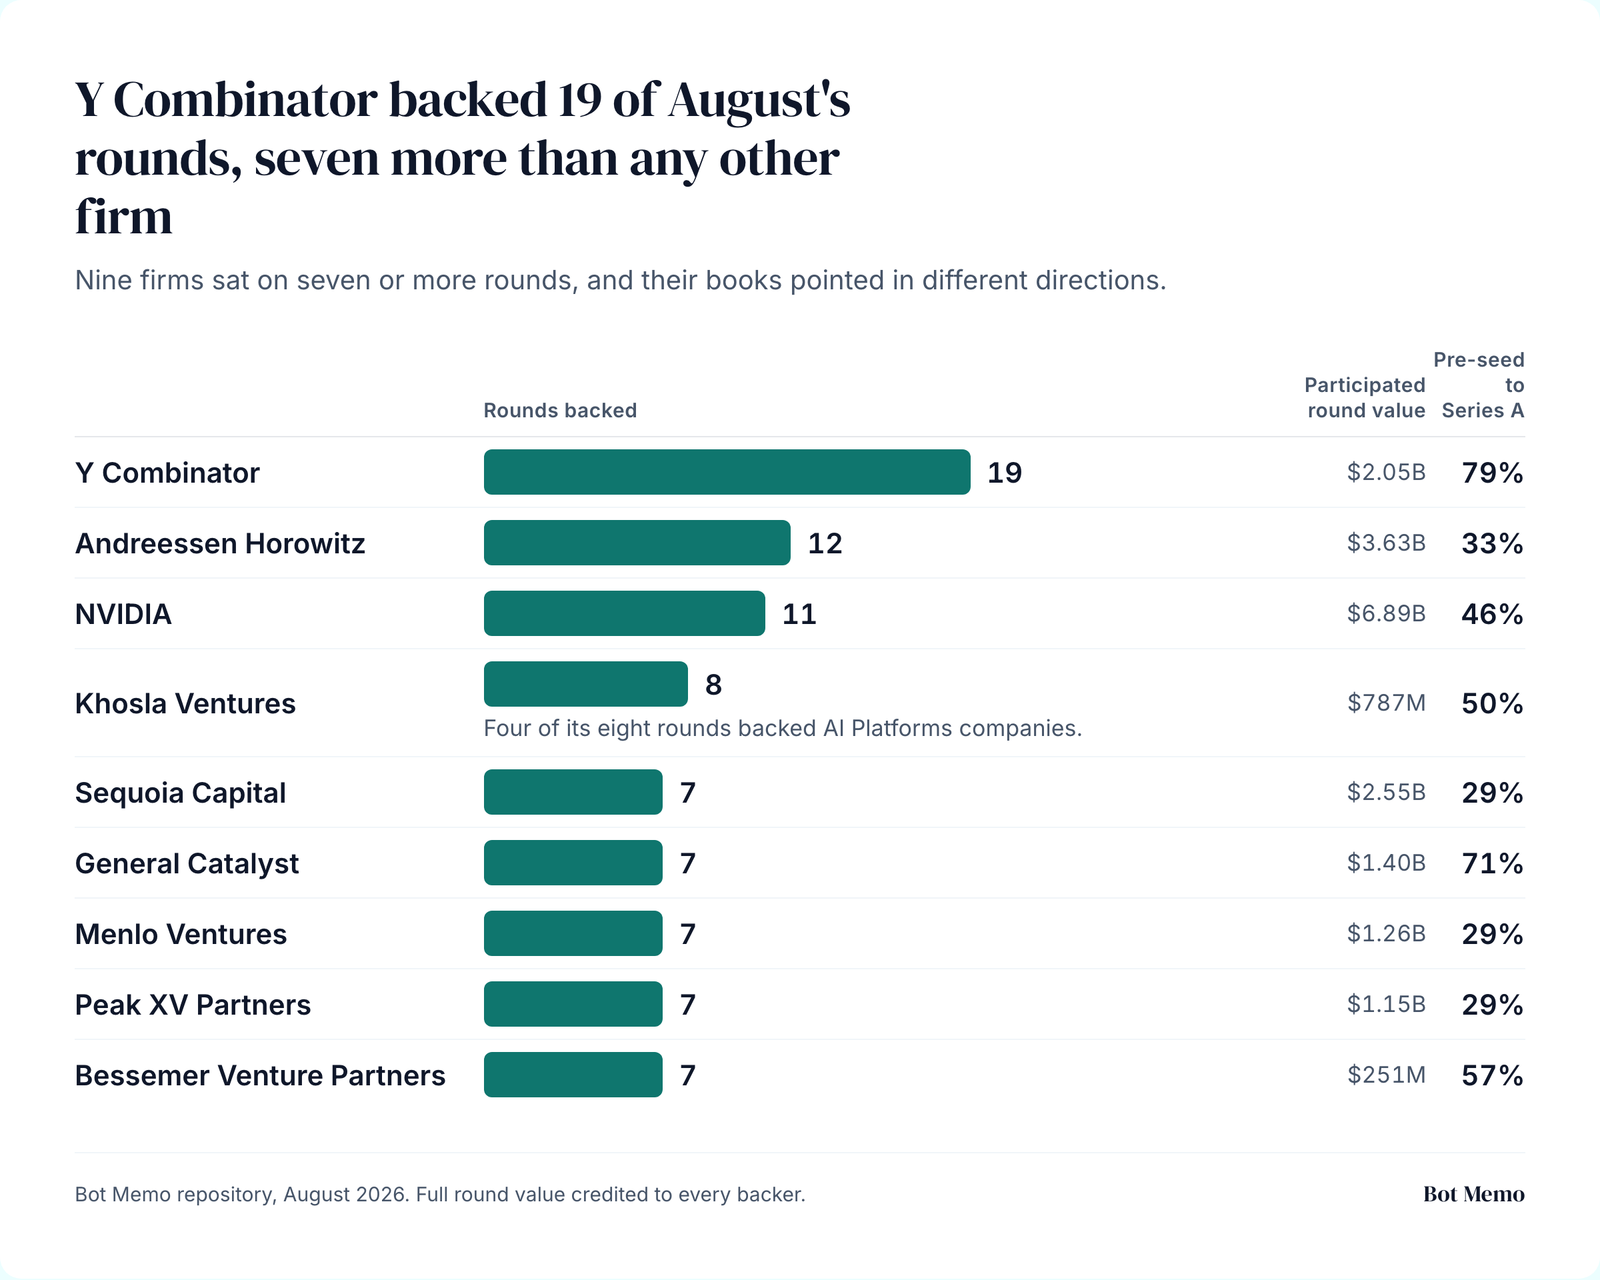
Below the nine firms on seven or more rounds, Spark Capital sat on six rounds carrying $1.25B of participated round value, five of them Series B or later. Conviction backed five worth $1.30B, three of them pre-seed through Series A. Antler took six, five of them at that early end. IDG Capital, Kaszek and Korea Development Bank backed four rounds each.
Syndicates got bigger. The average August round with disclosed backers carried 4.78 of them against 3.88 a year earlier, and 17.5% had a single backer, down from 20.9%. Series B rounds averaged 6.56 investors, up from 4.86, and only 8.3% of them were solo-backed.
Pre-seed and seed rounds got smaller. The median disclosed round was $3.8M, down from $4.2M a year ago, across 160 rounds against 135.
Where the dollars went
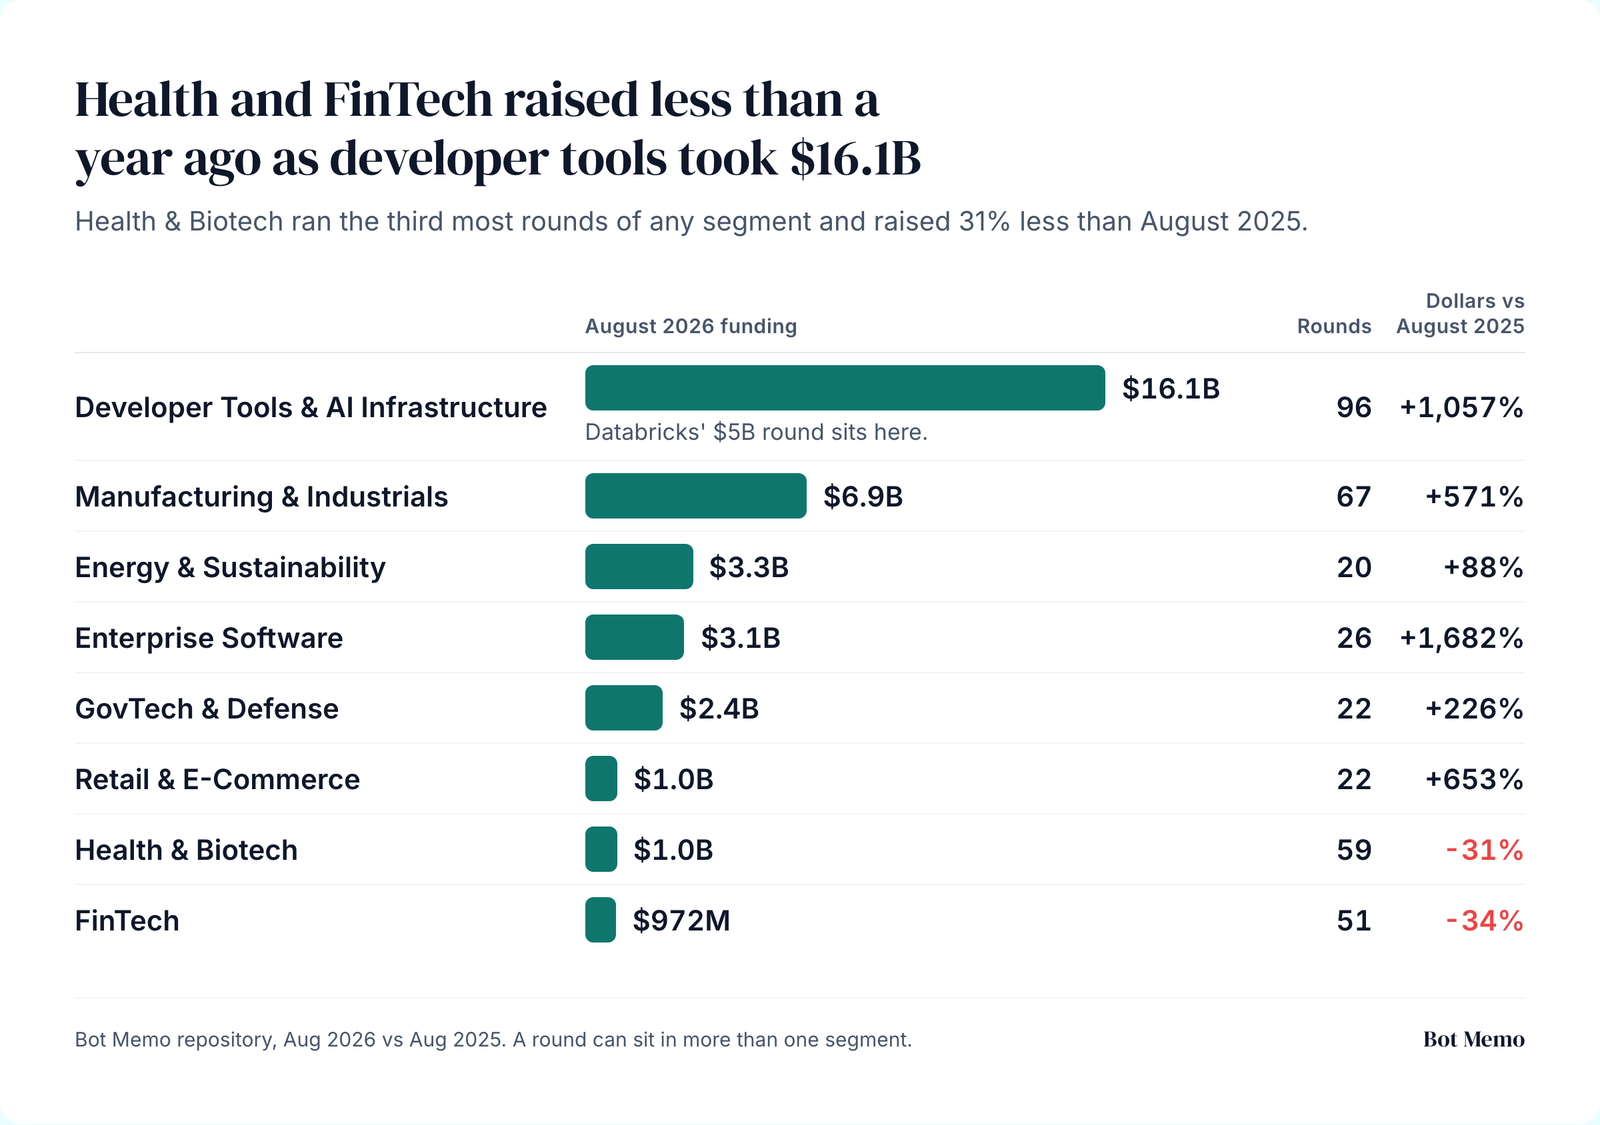
Developer tools and AI infrastructure took $16.1B across 96 rounds, 54.3% of the month's dollars. Manufacturing and industrial AI took $6.9B across 67 rounds.
Health & Biotech ran 59 rounds, the third most of any segment, and raised $1.0B, 31% less than August 2025. FinTech ran 51 rounds for $972M, down 34%. Health's round count rose 3.5% on the year while its dollars fell.
Companies building AI agents took 117 rounds and $9.6B, with a $9.7M median disclosed round, against 110 rounds and $2.4B last August. Databricks' $5B is more than half of that. Menlo Ventures backed five of the 117, behind only Y Combinator's seven.
Europe's early stage
Europe closed 77 rounds for $2.2B, against 70 rounds and $1.0B a year earlier. Its 54 early rounds raised $876.2M, up from $272.2M, and made up 22.4% of the world's early rounds, against 21.2%.
Sweden had 10 rounds, up from four, behind only the UK's 25. Norrsken Evolve backed four European rounds, more than any other investor in European rounds. A year ago the most active name there was High-Tech Gründerfonds, also on four.
Poll: You build GPU capacity or power for data centers. Would you take NVIDIA as your only named backer, or spend three more months building a syndicate?
Data: Bot Memo repository, 382 venture AI rounds, August 2026, all amounts USD. Full round value is attributed to every participating investor, so participated totals are never summed to a market figure.
About the author
Editorial Staff
The Editorial Staff at Bot Memo is a team of writers, analysts, and AI agents dedicated to mapping the global AI startup ecosystem. Led by Chintan Zalani, the team tracks thousands of funding rounds, classifies companies across verticals, and distills it all into actionable intelligence for investors and founders.