
AI startups raised $446.48B across 2,997 rounds with disclosed amounts in the first half of 2026 (January 1 to June 30). The largest was OpenAI’s $122B round, which closed on March 31. Capital was front-loaded: Q1 2026 booked $273.80B, then Q2 fell to $172.68B, a 36.9% quarter-over-quarter drop. Deal count barely moved, 1,509 rounds in Q1 against 1,488 in Q2. The median round was $11.21M while the mean was $148.98M, so the topline rests on a small number of very large deals. This report covers total funding, the largest rounds, sector shares, the stage split from pre-seed to late stage, and where the money landed.
On this page
- How much did AI startups raise in H1 2026?
- AI funding by quarter: Q1 vs Q2 2026
- Largest AI funding rounds in H1 2026
- Which sectors raised the most AI funding in H1 2026?
- AI funding by stage in H1 2026
- Where the AI money landed
- What H1 2026 signals for AI venture capital
- Methodology
- Frequently asked questions
How much did AI startups raise in H1 2026?
Global AI startup funding reached $446.48B across 2,997 rounds in the first half of 2026. The mean round came to $148.98M, but a handful of giant rounds pull that average up. The median round was $11.21M, a better read on what a typical AI startup raised.
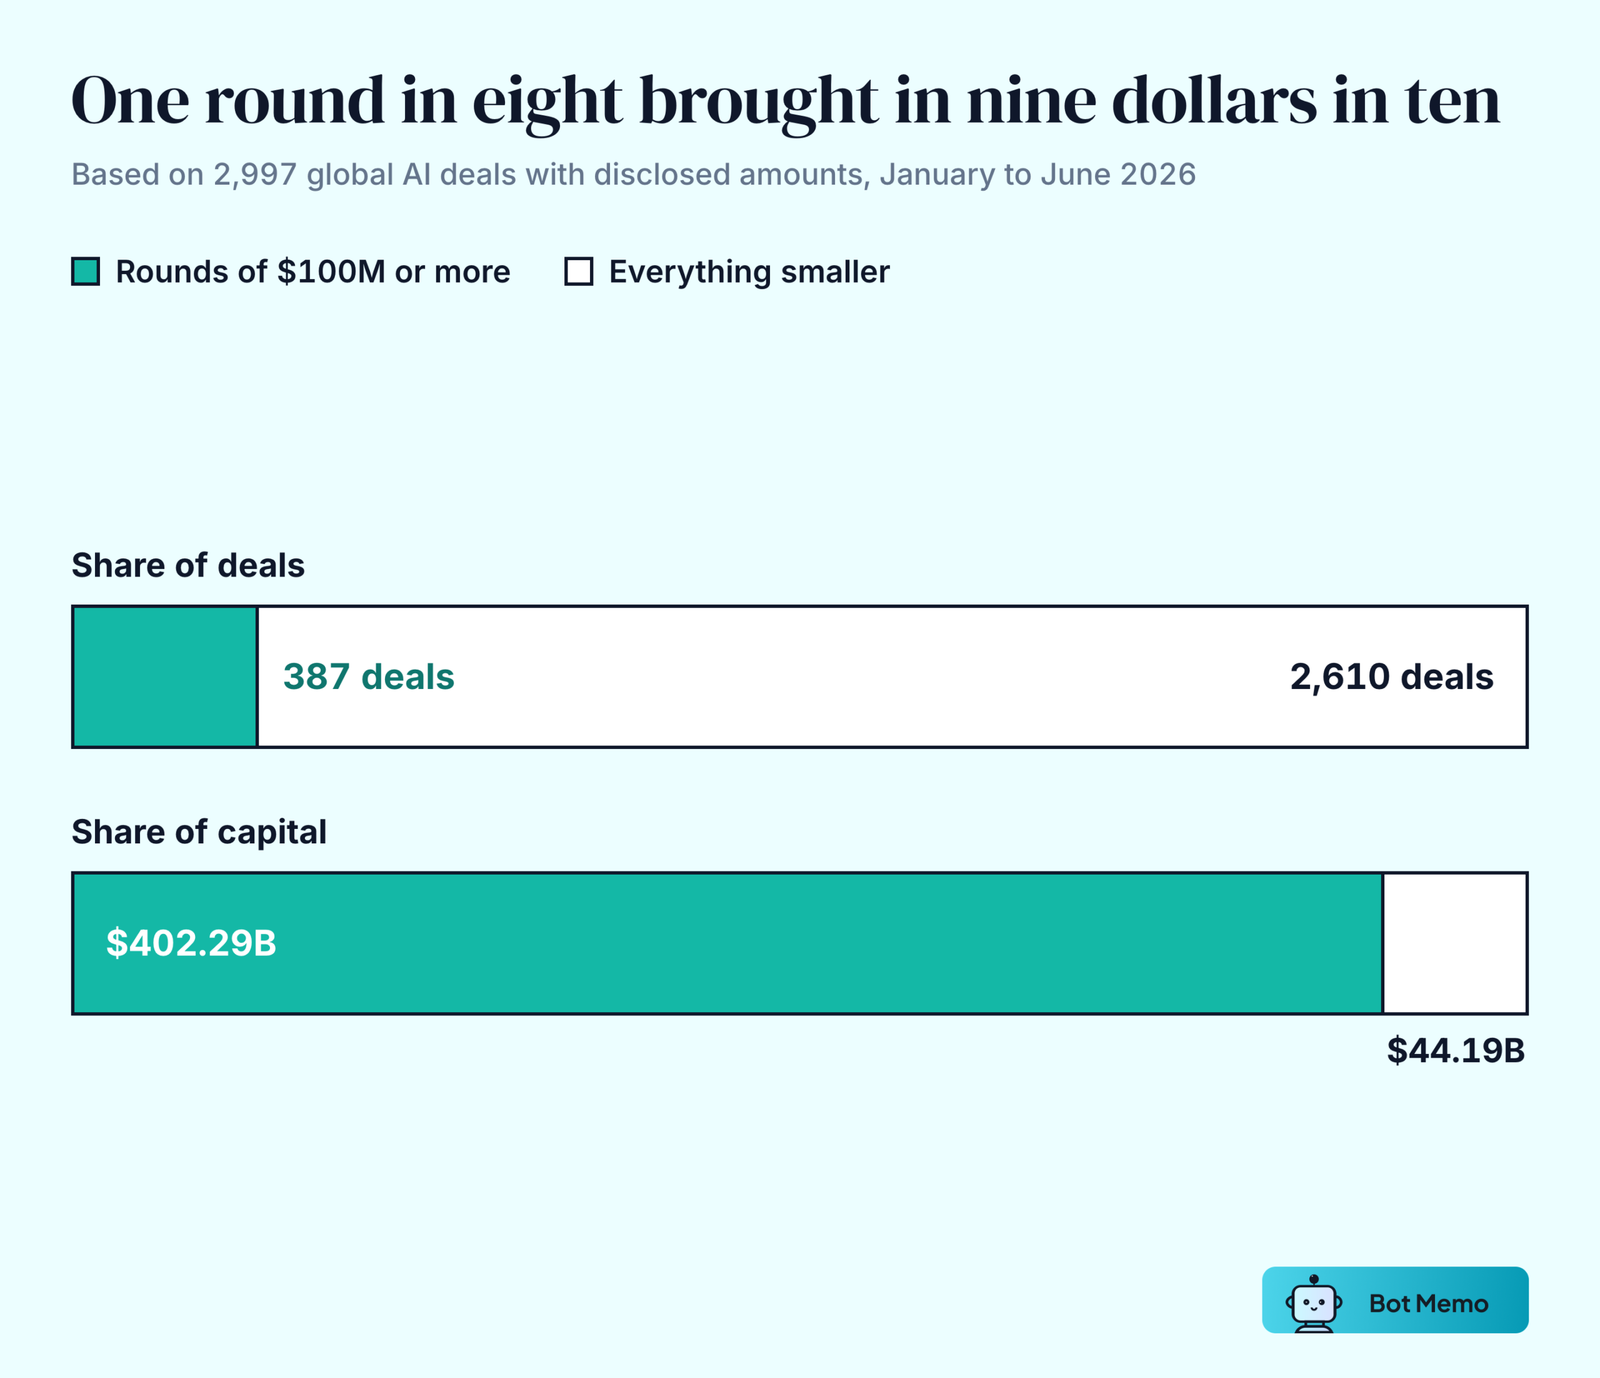
Concentration is the story. The 387 rounds of $100M or more, 12.9% of all rounds, captured 90.1% of every dollar raised in H1, $402.29B in total. The 2,345 rounds below $50M added up to $26.99B combined. The half was decided at the top of the market.
Frontier AI labs and AI infrastructure companies absorbed most of the capital, while thousands of smaller AI companies raised ordinary rounds far below the headline. The sections below separate the two layers so the numbers read clearly.
AI funding by quarter: Q1 vs Q2 2026
The two quarters tell opposite stories on dollars and deals:
| Quarter | Deals | Funding | Median deal | Mean deal |
|---|---|---|---|---|
| Q1 2026 | 1,509 | $273.80B | $12.33M | $181.45M |
| Q2 2026 | 1,488 | $172.68B | $10.51M | $116.05M |
Funding fell 36.9% quarter over quarter, but deal count barely moved. Almost the entire drop sat in the mega-round layer. Rounds of $100M or more fell from $250.75B in Q1 to $151.54B in Q2, while everything under $100M moved from $23.06B across 1,310 rounds to $21.14B across 1,300. The median round slipped from $12.33M to $10.51M, so the typical company kept raising at close to the same pace while the giant lab rounds cooled.
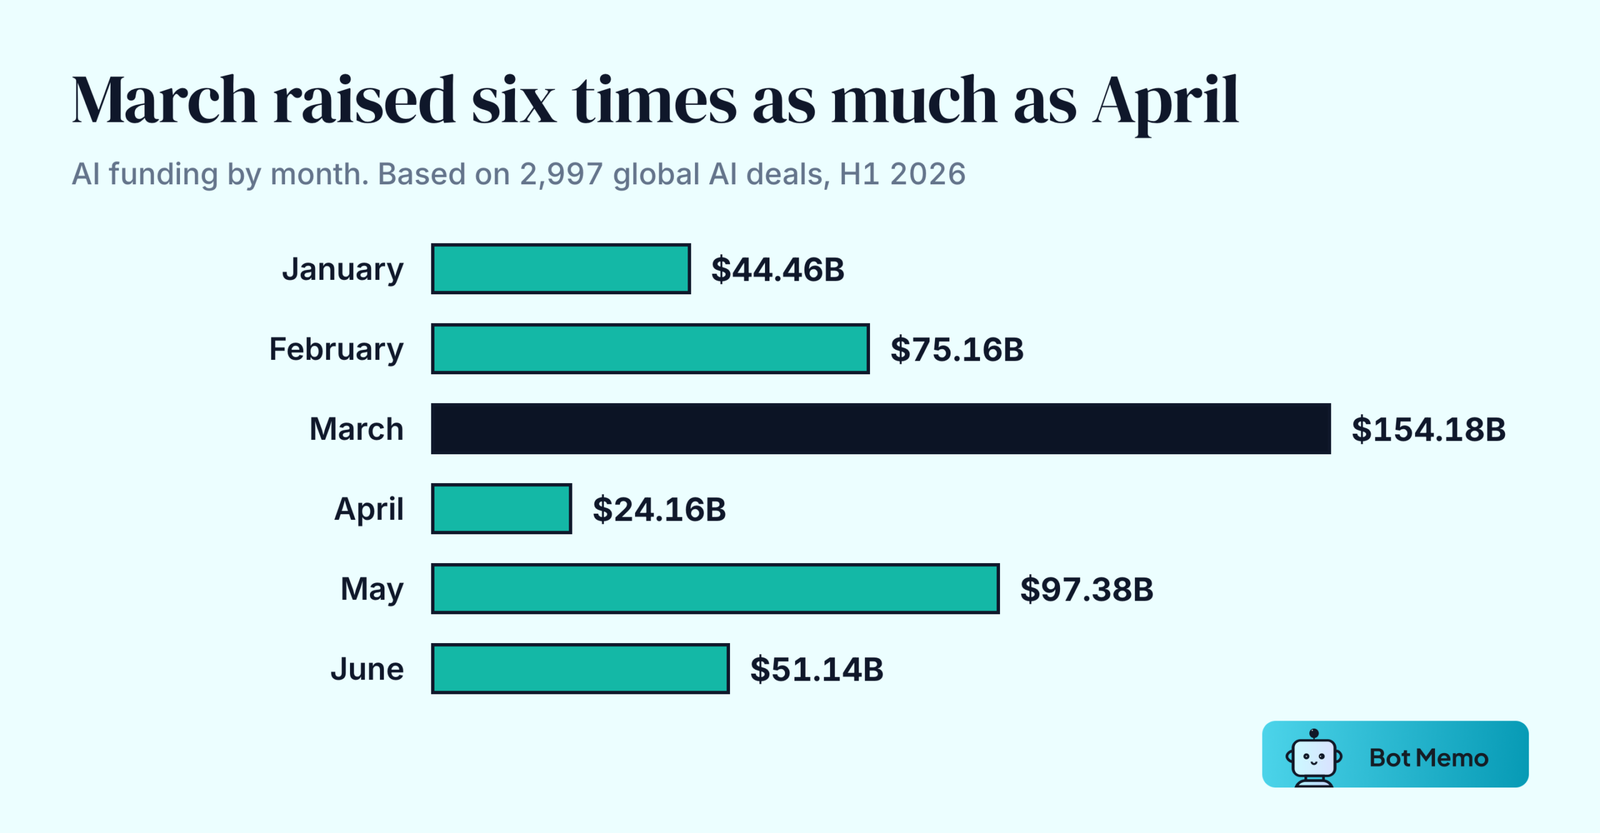
Monthly totals show the same swing. January raised $44.46B and February $75.16B (up 69.1%). March closed at $154.18B (up 105.1%), the peak of the half, carried by OpenAI’s round. April dropped to $24.16B (down 84.3%), May rebounded to $97.38B (up 303.1%) on Anthropic’s Series H, and June settled at $51.14B (down 47.5%). The spikes track the timing of the largest rounds.
Largest AI funding rounds in H1 2026
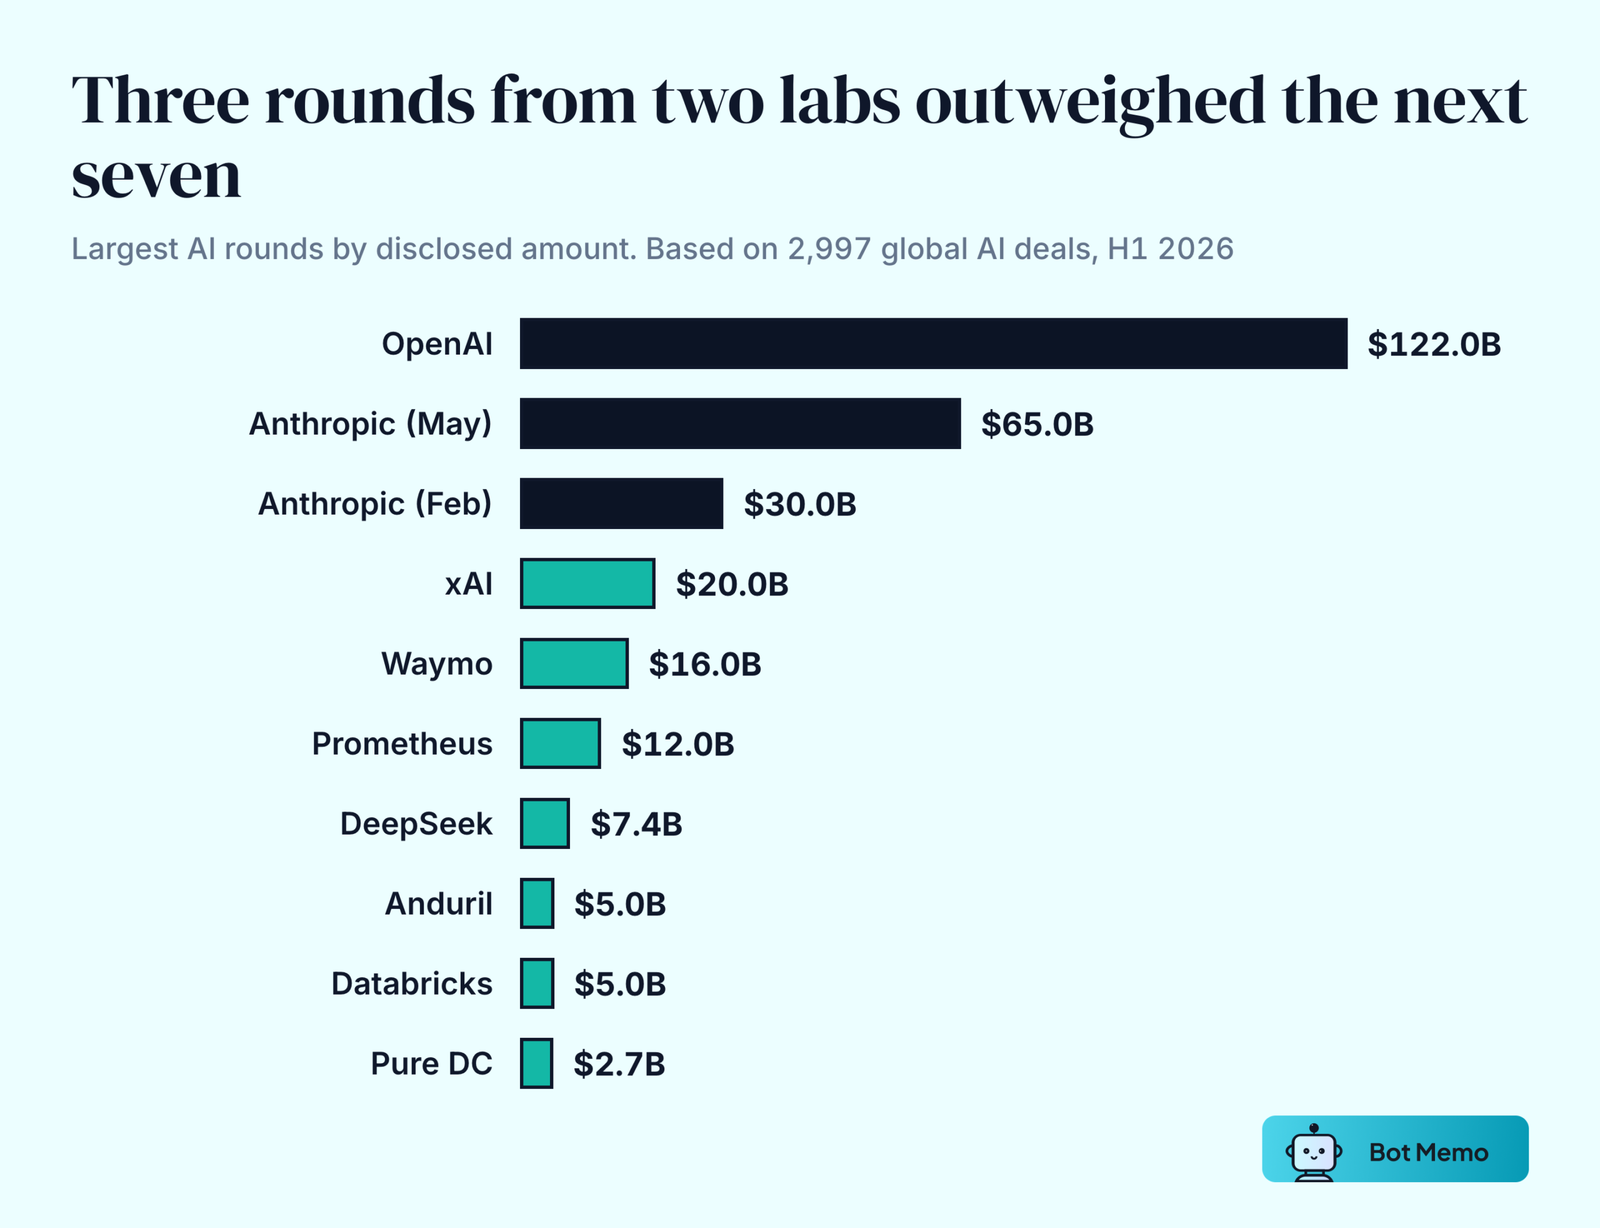
The ten biggest rounds of the half, by disclosed amount:
| Rank | Company | Country | Amount | Segment | Month |
|---|---|---|---|---|---|
| 1 | OpenAI | United States | $122.0B | Developer Tools & AI Infrastructure | March 2026 |
| 2 | Anthropic (Series H) | United States | $65.0B | Developer Tools & AI Infrastructure | May 2026 |
| 3 | Anthropic (Series G) | United States | $30.0B | Developer Tools & AI Infrastructure | February 2026 |
| 4 | xAI | United States | $20.0B | Developer Tools & AI Infrastructure | January 2026 |
| 5 | Waymo | United States | $16.0B | Transportation & Mobility | February 2026 |
| 6 | Prometheus | United States | $12.0B | Manufacturing & Industrials; Health & Biotech | June 2026 |
| 7 | DeepSeek | China | $7.4B | Developer Tools & AI Infrastructure | June 2026 |
| 8 | Anduril | United States | $5.0B | GovTech & Defense | May 2026 |
| 9 | Databricks | United States | $5.0B | Developer Tools & AI Infrastructure | February 2026 |
| 10 | Pure DC (debt) | United Kingdom | $2.7B | Energy & Sustainability | May 2026 |
OpenAI’s $122B and Anthropic’s two rounds ($65B and $30B) sit far above the rest of the field, $217B between them. Below the top three, deal sizes drop fast into the $5B to $20B range. The ten rounds together came to $285.1B, 63.9% of all H1 capital. Eight of the ten went to United States companies, and six fell inside Developer Tools and AI Infrastructure. DeepSeek’s round, its first from outside investors, was reported by the press and not announced by the company. Databricks counts the equity only, not the debt capacity raised alongside it. Pure DC’s $2.7B is a debt facility for its data-center build-out.
Which sectors raised the most AI funding in H1 2026?
Sector shares for the first half of 2026, ranked by capital raised. A company that operates in more than one sector is counted in full in each, so the shares add up to more than 100%.
| Segment | Funding | Deals | Share of H1 dollars |
|---|---|---|---|
| Developer Tools & AI Infrastructure | $294.88B | 444 | 66.0% |
| Manufacturing & Industrials | $44.36B | 357 | 9.9% |
| Health & Biotech | $30.08B | 442 | 6.7% |
| Transportation & Mobility | $27.32B | 162 | 6.1% |
| FinTech | $21.07B | 425 | 4.7% |
| Energy & Sustainability | $19.53B | 197 | 4.4% |
| GovTech & Defense | $16.95B | 165 | 3.8% |
| Cybersecurity | $7.61B | 187 | 1.7% |
| Marketing & Sales Tech | $6.50B | 236 | 1.5% |
Developer Tools and AI Infrastructure took 66.0% of all H1 dollars, the model-and-compute layer that houses OpenAI, Anthropic and xAI. That one segment raised more than the next eight sectors combined. Below it, Manufacturing and Industrials pulled $44.36B across 357 deals, lifted by Prometheus, ahead of Health and Biotech at $30.08B.
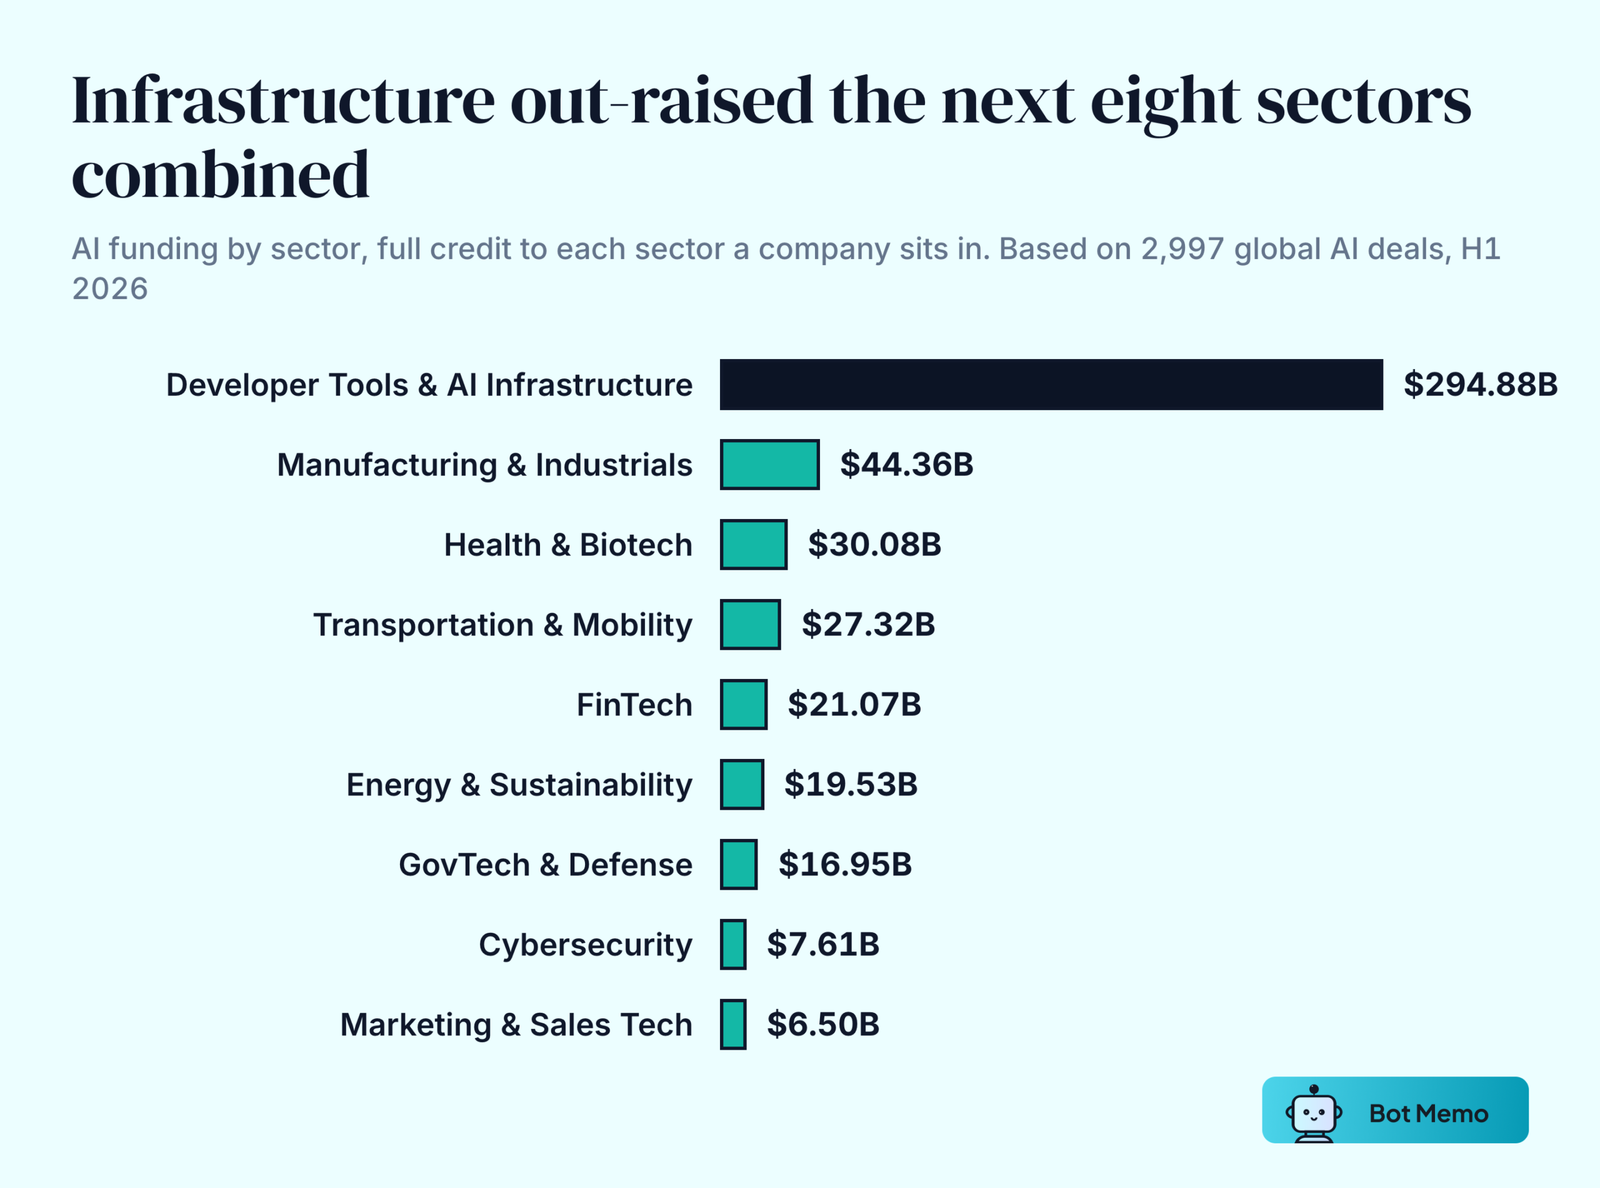
Deal count tells a different story than dollars. Health and Biotech recorded the most rounds of any applied sector at 442, and FinTech followed at 425. Both closed far more rounds than their funding share suggests, a broad application economy raising smaller checks beneath the infrastructure giants.
AI funding by stage in H1 2026
The stage split shows where deal count and capital diverge:
| Stage | Deals | Funding |
|---|---|---|
| Pre-Seed | 319 | $0.85B |
| Seed | 892 | $10.66B |
| Series A | 733 | $29.96B |
| Series B | 310 | $39.03B |
| Series C | 146 | $24.69B |
| Series D | 64 | $14.54B |
| Series E | 24 | $24.62B |
| Series F | 14 | $6.49B |
| Series G+ | 17 | $110.99B |
| Strategic | 27 | $140.52B |
| Growth | 109 | $9.12B |
| Debt | 65 | $17.90B |
| Convertible | 1 | $0.03B |
| Stage not stated | 276 | $17.09B |
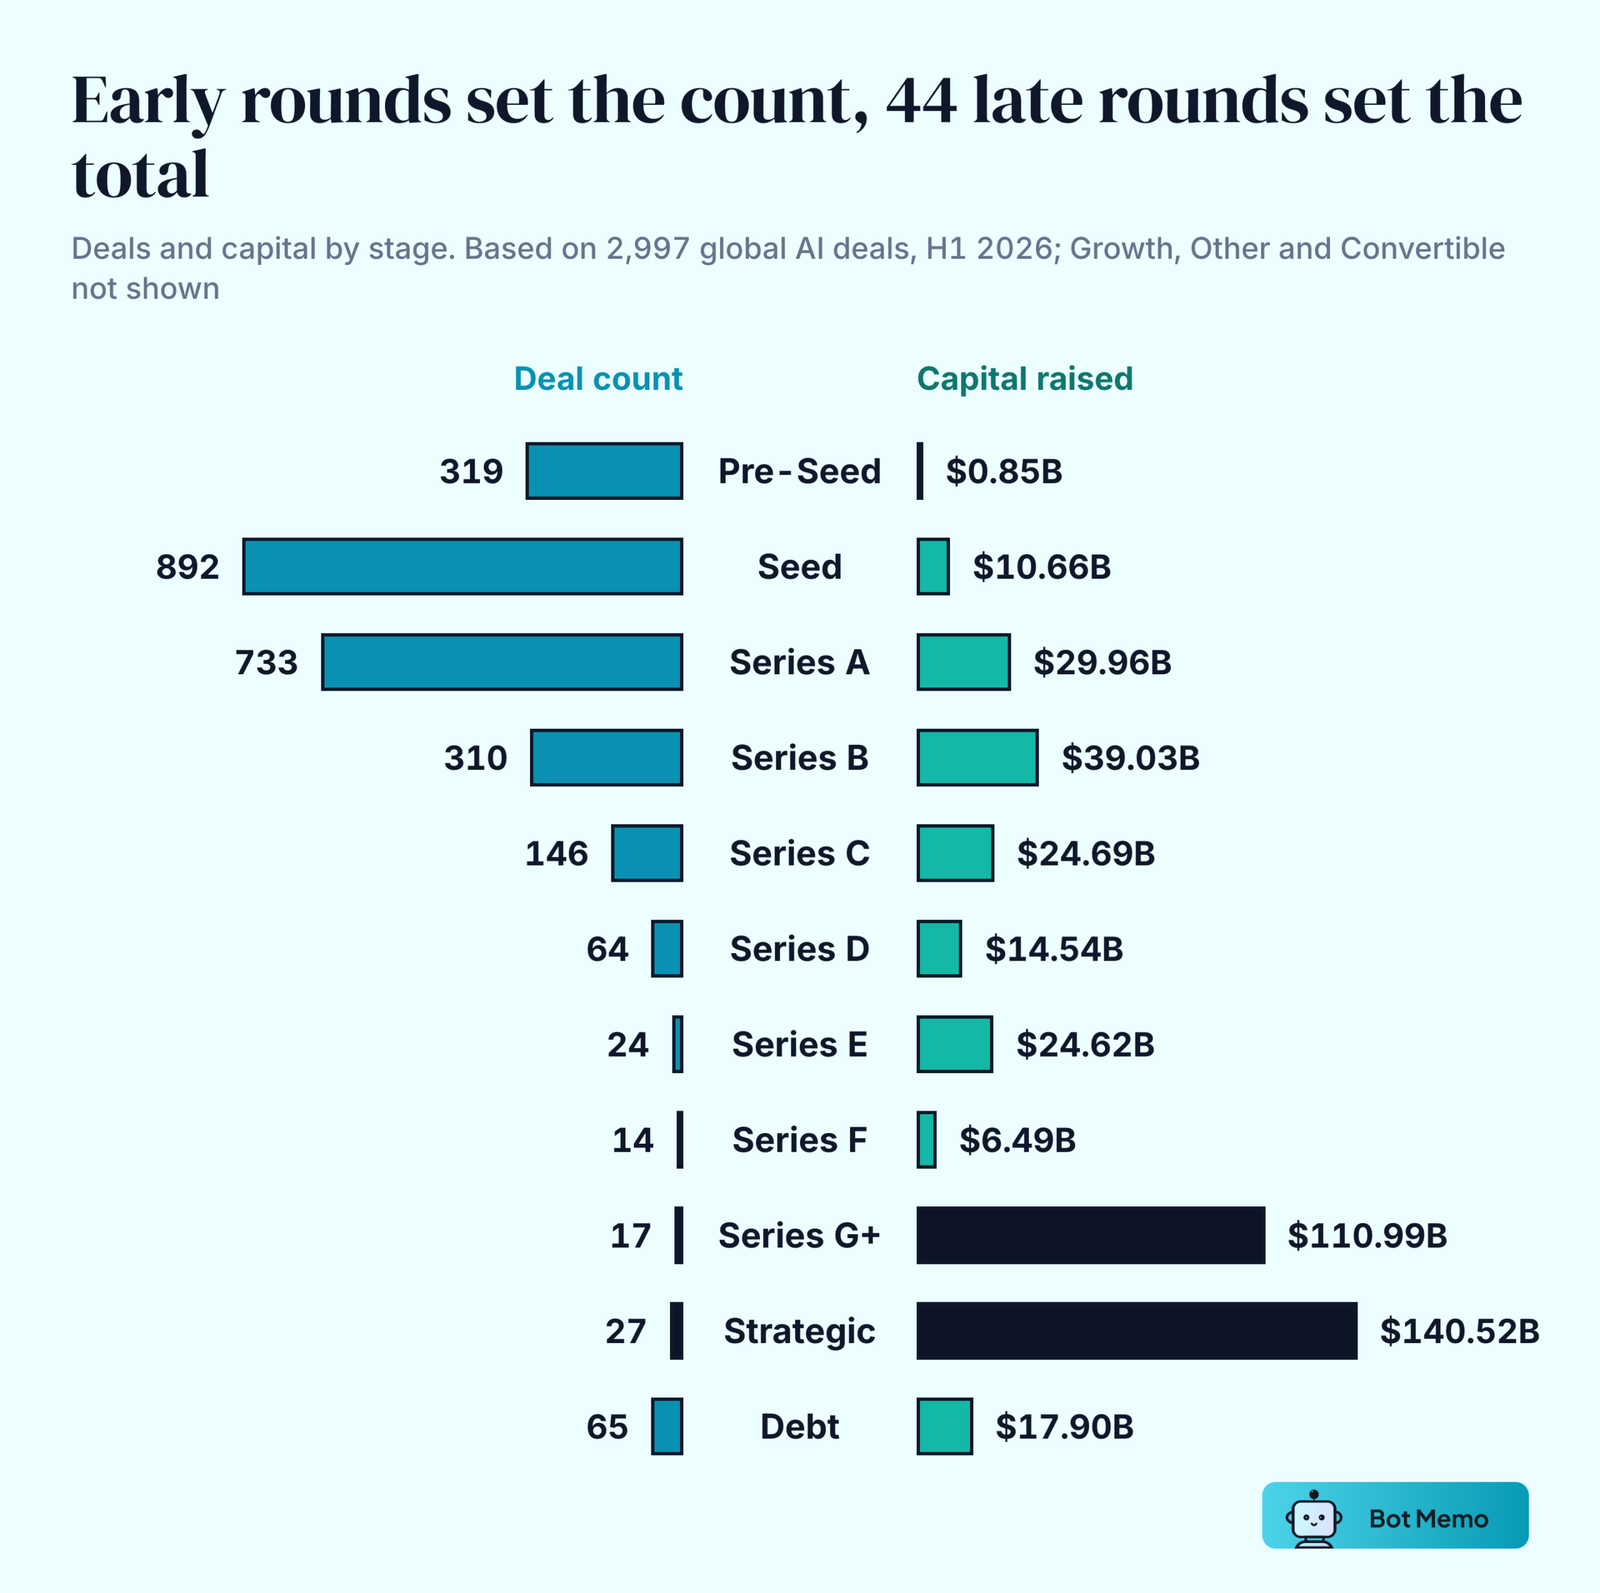
Seed and Series A produced the most rounds, 1,625 combined, but a short list of late-stage and strategic deals carried the dollars. The 27 strategic rounds accounted for $140.52B and the 17 Series G and later rounds added $110.99B. Those 44 rounds raised $251.51B, 56.3% of H1 capital. Debt was its own lane at $17.90B across 65 deals, much of it data-center and compute financing rather than equity. For how round sizes step up from one stage to the next, see our breakdown of AI startups by funding stage.
Where the AI money landed
United States companies raised $365.60B across 1,358 rounds, 81.9% of the dollars but 45.3% of the rounds. The United Kingdom followed at $20.60B across 269 rounds, then China at $17.27B across 67. India closed 305 rounds, more than the United Kingdom, for $6.21B.
Within the United States, funding pooled in one metro. Companies headquartered in the San Francisco Bay Area raised $308.71B across 525 rounds, 69.1% of the global total. OpenAI, both Anthropic rounds, Prometheus and Databricks are based in San Francisco, xAI in Palo Alto and Waymo in Mountain View. New York City raised $19.34B across 342 rounds at far smaller average sizes. Outside the United States, London led with $18.64B across 213 rounds.
The regional editions go deeper: US AI funding in H1 2026 covers the US market by city, sector and investor, and Europe AI funding in H1 2026 covers the European market. Our AI startup funding by city ranking tracks the city-level picture.
What H1 2026 signals for AI venture capital
Read the tables together and one theme runs through them. AI startup funding in the first half of 2026 was a story of capital concentration. The $446.48B topline is real, but it rests on a short list of frontier AI labs and AI infrastructure providers whose rounds each cleared several billion dollars. Strip those out and the market that remains is an ordinary one, with a median AI deal near $11.21M and a steady flow of seed and Series A rounds.
For founders, the read is practical. Early-stage funding held up, so a strong seed or Series A round was still achievable across sectors and geographies. The scarce resource was late-stage capital at scale, which flowed to a handful of AI companies building foundation models, compute and data-center capacity.
For investors, the H1 2026 numbers are a reminder that headline totals overstate momentum. The 36.9% quarter-over-quarter drop in dollars came almost entirely from rounds of $100M or more, while deal count barely moved. At the 2026 midpoint, AI venture capital is two markets under one label: a concentrated set of billion-dollar rounds, and a wide, global base of smaller AI startups raising at a normal pace.
Methodology
Figures cover AI startup funding rounds dated January 1 to June 30, 2026, from the Bot Memo repository of verified, deduplicated and AI-classified rounds. Totals count only rounds with a disclosed amount, converted to US dollars. Secondary share sales and financings by public companies are excluded from every total, so CoreWeave’s March financing does not appear. Debt rounds raised by private AI companies are included and shown as their own stage. Sector figures give full credit to each sector a company operates in. City figures follow the company’s headquarters, and a company with more than one headquarters city is counted in each.
Frequently asked questions
How much did AI startups raise globally in H1 2026?
AI startups raised $446.48B across 2,997 rounds with disclosed amounts between January 1 and June 30, 2026.
What was the largest AI funding round in H1 2026?
OpenAI’s $122B round, which closed on March 31, 2026. It was the biggest single AI financing of the half.
Which sector raised the most AI funding in H1 2026?
Developer Tools and AI Infrastructure led with $294.88B across 444 deals, 66.0% of all dollars, driven by the largest foundation-model rounds.
What was the typical AI deal size in H1 2026?
The median AI deal was $11.21M. The mean was $148.98M, pulled up by a small number of billion-dollar rounds.
Did AI funding slow down in 2026?
Funding fell 36.9% from Q1 ($273.80B) to Q2 ($172.68B), but deal count held nearly flat at 1,509 then 1,488. The drop came from fewer mega-rounds; rounds under $100M raised close to the same amount in both quarters.
How concentrated was AI funding in H1 2026?
The 387 rounds of $100M or more captured 90.1% of all capital raised, $402.29B of the $446.48B total.
About the author
Editorial Staff
The Editorial Staff at Bot Memo is a team of writers, analysts, and AI agents dedicated to mapping the global AI startup ecosystem. Led by Chintan Zalani, the team tracks thousands of funding rounds, classifies companies across verticals, and distills it all into actionable intelligence for investors and founders.